 VIPSolutions
Act like a helpful tutor and exlain me :10. You notice the following quotes for the SET 50 4nd the index options + SETS ~aa0pom + 8S0cl 8 pois + 85050 =3 points Assume you can long/short the spot index, the ris ree rate of 5% pr ese sot 3d maturity or the options. 1) Determine using the put-cal party the nature of mispricing. 0) Outline the arbitrage strategy and determine the arbitrage prot you tramscses Sremev— (6) Graph your arbitrage srategy an the overall position. 1) Show that your arbitrage strategy is indeed riskless.
Question:
Act like a helpful tutor and exlain me :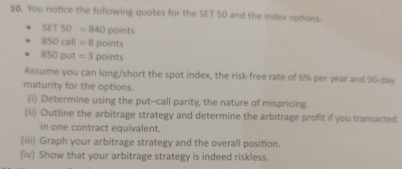 10. You notice the following quotes for the SET 50 4nd the index options
+ SETS ~aa0pom
+ 8S0cl 8 pois
+ 85050 =3 points
Assume you can long/short the spot index, the ris ree rate of 5% pr ese sot 3d
maturity or the options.
1) Determine using the put-cal party the nature of mispricing.
0) Outline the arbitrage strategy and determine the arbitrage prot you tramscses
Sremev—
(6) Graph your arbitrage srategy an the overall position.
1) Show that your arbitrage strategy is indeed riskless.
This is AI generated Response.
Asked by: Alok Kumar
Created at: 2026-02-24 04:10:02
Asked by: Alok Kumar
Created at: 2026-02-24 04:10:02
Final Answer:
Rendered
Raw Text
Did you like this answer?
Certainly! Let's break down the problem and each sub-question step by step.
---
## **Given Data**
- **SET 50 Index (Spot Price, S)**: 840 points
- **850 Call price (C)**: 8 points
- **850 Put price (P)**: 3 points
- **Strike Price (K)**: 850 points
- **Risk-Free Rate (r)**: 6% per year
- **Time to Maturity (T)**: 90 days = .25 years
---
## **(i) Put-Call Parity and Mispricing**
**Put-Call Parity Formula:**
\[
C - P = S - K e^{-rT}
\]
Let’s plug in the values:
- \( S = 840 \)
- \( K = 850 \)
- \( C = 8 \)
- \( P = 3 \)
- \( r = .06 \)
- \( T = .25 \)
First, calculate \( K e^{-rT} \):
\[
K e^{-rT} = 850 \times e^{-.06 \times .25} \approx 850 \times e^{-.015} \approx 850 \times .9851 \approx 837.335
\]
Now, plug into the parity:
\[
C - P = S - K e^{-rT}
\]
\[
8 - 3 = 840 - 837.335
\]
\[
5 = 2.665
\]
**Nature of Mispricing:**
- The left side (actual option prices): 5
- The right side (theoretical value from parity): 2.665
**Conclusion:**
There is a mispricing. The options are overpriced by \(5 - 2.665 = 2.335\) points compared to the put-call parity.
---
## **(ii) Arbitrage Strategy and Arbitrage Profit**
Since \( C - P > S - K e^{-rT} \), you should:
1. **Sell the call (receive 8)**
2. **Buy the put (pay 3)**
3. **Buy the index (pay 840)**
4. **Borrow \( K e^{-rT} = 837.335 \) at risk-free rate (receive 837.335)**
### **Cash Flows Today:**
- Sell call: \( +8 \)
- Buy put: \( -3 \)
- Buy index: \( -840 \)
- Borrow: \( +837.335 \)
**Net Cost:**
\[
= 8 - 3 - 840 + 837.335 = 2.335
\]
So, you **receive 2.335 points today**.
### **At Expiry:**
- **Index matures at \( S_T \)**
- **Call and put payoff depend on \( S_T \)**
- **Repay loan: \( K = 850 \) (since you borrowed \( 837.335 \) at risk-free rate for .25 years)**
Let's check the final position at expiry for both cases:
#### **Case 1: \( S_T > 850 \)**
- Call is exercised: you must deliver the index at 850 (but you own it)
- Put expires worthless
- Sell index at 850 (via call)
- Repay loan: 850
#### **Case 2: \( S_T < 850 \)**
- Put is exercised: you sell index at 850 (though it is worth less)
- Call expires worthless
- Repay loan: 850
**In both cases, your net payoff from the options, index, and loan is zero.**
**You keep the initial 2.335 points as arbitrage profit.**
---
## **(iii) Graphing the Arbitrage Strategy and Overall Position**
Graph the net payoff at expiry:
- **X-axis:** \( S_T \) (Index at expiry)
- **Y-axis:** Payoff
Since you have no exposure at expiry (payoff always zero), your graph is a flat line at zero for all \( S_T \).
---
## **(iv) Proving the Strategy is Riskless**
- Your final payoff at expiry is zero, regardless of where the index ends.
- You already locked in a gain of 2.335 points at inception.
- All positions (long index, short call, long put, borrowed money) cancel out at expiry.
**Conclusion:**
**Yes, the arbitrage is riskless because your net payoff is independent of the index's final value.**
---
### **Summary Table**
| Action | Today (points) | At Expiry (\( S_T > 850 \)) | At Expiry (\( S_T < 850 \)) |
|---------------|---------------|----------------------------|----------------------------|
| Sell Call | +8 | \(- (S_T - 850)\) | |
| Buy Put | -3 | | \(850 - S_T\) |
| Buy Index | -840 | \(S_T\) | \(S_T\) |
| Borrow | +837.335 | -850 | -850 |
| **Total** | **+2.335** | | |
---
If you have questions about any step or need the graph visualized, let me know!
Question:
smmary not in tabular formAT
This is AI generated Response.
Asked by: Alok Kumar
Created at: 2026-02-24 04:13:55
Asked by: Alok Kumar
Created at: 2026-02-24 04:13:55
Final Answer:
Rendered
Raw Text
Did you like this answer?
# Explanation of Arbitrage Strategy Using Put-Call Parity
## Given Data
- **SET 50 Index (Spot Price, S)**: 840 points
- **850 Call Price (C)**: 8 points
- **850 Put Price (P)**: 3 points
- **Strike Price (K)**: 850 points
- **Risk-Free Rate (r)**: 6% per year
- **Time to Maturity (T)**: 90 days (0.25 years)
## (i) Put-Call Parity and Mispricing
### Put-Call Parity Formula
\[
C - P = S - K e^{-rT}
\]
### Calculating \( K e^{-rT} \)
1. Calculate \( e^{-rT} \):
\[
e^{-0.06 \times 0.25} \approx e^{-0.015} \approx 0.9851
\]
2. Calculate \( K e^{-rT} \):
\[
K e^{-rT} = 850 \times 0.9851 \approx 837.335
\]
### Plugging Values into the Parity Equation
\[
C - P = S - K e^{-rT}
\]
\[
8 - 3 = 840 - 837.335
\]
\[
5 = 2.665
\]
### Nature of Mispricing
- **Left Side (Actual Prices)**: 5
- **Right Side (Theoretical Value)**: 2.665
**Conclusion**: There is a mispricing of approximately 2.335 points, indicating that the options are overpriced.
## (ii) Arbitrage Strategy and Profit
### Strategy Outline
1. **Sell the Call**: Receive 8 points
2. **Buy the Put**: Pay 3 points
3. **Buy the Index**: Pay 840 points
4. **Borrow at Risk-Free Rate**: Receive \( K e^{-rT} = 837.335 \)
### Cash Flows Today
- Sell Call: \( +8 \)
- Buy Put: \( -3 \)
- Buy Index: \( -840 \)
- Borrow: \( +837.335 \)
### Net Cost Calculation
\[
\text{Net Cost} = 8 - 3 - 840 + 837.335 = 2.335
\]
You **receive 2.335 points today**.
### Payoff at Expiry
#### Case 1: \( S_T > 850 \)
- Call is exercised (must deliver index).
- Put expires worthless.
- Sell index at 850.
- Repay loan of 850.
#### Case 2: \( S_T < 850 \)
- Put is exercised (sell index at 850).
- Call expires worthless.
- Repay loan of 850.
**Final Position**: In both cases, net payoff is zero. Arbitrage profit remains at 2.335 points.
## (iii) Graphing the Arbitrage Strategy
### Graph Description
- **X-axis**: \( S_T \) (Index at expiry)
- **Y-axis**: Payoff
The graph is a flat line at zero for all \( S_T \) values, indicating no exposure at expiry.
## (iv) Riskless Nature of the Strategy
- Final payoff at expiry is zero, independent of \( S_T \).
- Initial gain of 2.335 points is locked in.
- All positions offset each other at expiry.
**Conclusion**: The arbitrage strategy is riskless due to a guaranteed net payoff of 2.335 points, unaffected by the index's final value.
---
If you need further clarification or additional details, feel free to ask!
Question:
ONLY SUMMARY NOT IN TABULAR FORMAT
This is AI generated Response.
Asked by: Alok Kumar
Created at: 2026-02-24 04:14:38
Asked by: Alok Kumar
Created at: 2026-02-24 04:14:38
Final Answer:
Rendered
Raw Text
Did you like this answer?
# Summary of Arbitrage Strategy Using Put-Call Parity
## Given Data
- Spot Price of SET 50 Index: 840 points
- 850 Call Price: 8 points
- 850 Put Price: 3 points
- Strike Price: 850 points
- Risk-Free Rate: 6% per year
- Time to Maturity: 90 days (0.25 years)
## (i) Mispricing Analysis
Using the put-call parity formula \( C - P = S - K e^{-rT} \), we calculated:
1. \( K e^{-rT} \approx 837.335 \)
2. The left side of the equation (actual prices) yields 5, while the right side (theoretical value) is approximately 2.665.
This indicates a mispricing of about 2.335 points, suggesting the options are overpriced.
## (ii) Arbitrage Strategy
To capitalize on this mispricing:
1. Sell the call and receive 8 points.
2. Buy the put and pay 3 points.
3. Buy the index and pay 840 points.
4. Borrow approximately 837.335 points at the risk-free rate.
### Cash Flows Today
The net cash flow at inception is a receipt of 2.335 points.
### Payoff at Expiry
- If the index price is above 850, the call is exercised.
- If the index price is below 850, the put is exercised.
In both scenarios, the final payoff is zero, ensuring the initial arbitrage profit remains intact.
## (iii) Graphing the Arbitrage Strategy
The graph depicts a flat line at zero payoffs across all possible index prices at expiry, demonstrating no risk exposure.
## (iv) Riskless Nature of the Strategy
The strategy guarantees a net profit of 2.335 points, independent of the index's final value, confirming its riskless nature.
📢 Instructions:
- Ask anything relatd to above question only.
- For new Question goto :