 VIPSolutions
Now give this answer completely without skipping even a small step of calculation and try not to give answer in long paragraphs and answer the questions by following these instructions: ?Solution should be in proper format. ?A complete answer starts with the problem's objective OR addition of available data/ information Or the right approach. ?Add all necessary steps/supporting explanations until the answer is complete. ?If there are any formulae, you should mention it. ?Write calculations in a format so it can be easily pasted in chegg equation render tool. ?Do not use Python or any code-based for calculations (Important). ?Double check the solution to accomplish the correct concept, explanation, and calculations before submitting. ✅ The Final Answer should be a simple and clear summary of the solution in lucid language. ✅ The Final Answer Step is to include the crux of the entire solution. ✅ The final answer step contains the result of the solution only in a clear & concise manner. ✅ The Final Answer should be a simple and clear summary of the solution in lucid language. ✅ Final Answer Step is to include the crux of the entire solution. ✅Final answer step contains the result of the solution only in clear & concise manner.Required: a. Assuming that the expectations hypothesis is valid, compute the expected price of the four-year zero coupon bond shown below at the end of (i) the first year; (i) the second year; (i) the third year; (i) the fourth year. b. What is the rate of return of the bond in years 1, 2, 3, and 4? Conclude that the expected return equals the forward rate for each year, ‘Complete this question by entering your answers in the tabs below. i Required A Required B a Assuming that the expectations hypothesis is valid, compute the expected price of the four-year zero coupon bond shown below at the end of (i) the first year; (il) the second year; (ii) the third year; (Iv) the fourth year. Note: Do not round intermediate calculations. Round your answers to 2 decimal places. ~ Er En TE PR BE Eee ET 5 = Erma me i x
Question:
Now give this answer completely without skipping even a small step of calculation and try not to give answer in long paragraphs and answer the questions by following these instructions:
?Solution should be in proper format.
?A complete answer starts with the problem's objective OR addition of available data/ information Or the right approach.
?Add all necessary steps/supporting explanations until the answer is complete.
?If there are any formulae, you should mention it.
?Write calculations in a format so it can be easily pasted in chegg equation render tool.
?Do not use Python or any code-based for calculations (Important).
?Double check the solution to accomplish the correct concept, explanation, and calculations before submitting.
✅ The Final Answer should be a simple and clear summary of the solution in lucid language.
✅ The Final Answer Step is to include the crux of the entire solution.
✅ The final answer step contains the result of the solution only in a clear & concise manner.
✅ The Final Answer should be a simple and clear summary of the solution in lucid language.
✅ Final Answer Step is to include the crux of the entire solution.
✅Final answer step contains the result of the solution only in clear & concise manner.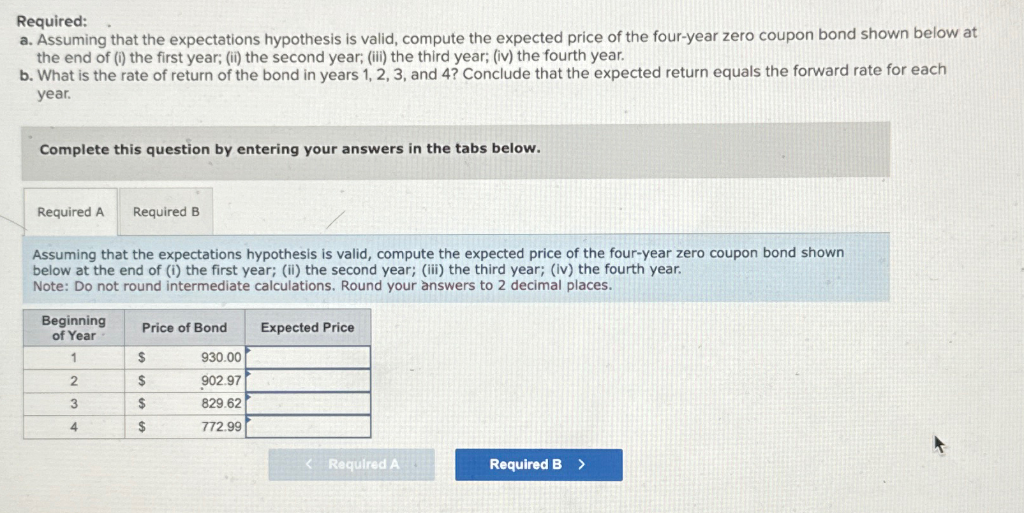 Required:
a. Assuming that the expectations hypothesis is valid, compute the expected price of the four-year zero coupon bond shown below at
the end of (i) the first year; (i) the second year; (i) the third year; (i) the fourth year.
b. What is the rate of return of the bond in years 1, 2, 3, and 4? Conclude that the expected return equals the forward rate for each
year,
‘Complete this question by entering your answers in the tabs below. i
Required A Required B a
Assuming that the expectations hypothesis is valid, compute the expected price of the four-year zero coupon bond shown
below at the end of (i) the first year; (il) the second year; (ii) the third year; (Iv) the fourth year.
Note: Do not round intermediate calculations. Round your answers to 2 decimal places.
~
Er En
TE PR BE
Eee ET
5 = Erma me
i
x
Asked by: JAYANTH POTHALA
Created at: 2025-09-28 08:41:35
Final Answer:
📢 Instructions:
- Ask anything relatd to above question only.
- For new Question goto :