Hide student question
Time Left :
01
:
54
:
45
Student question
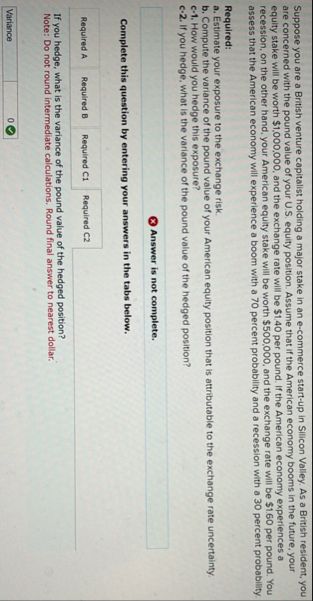
Suppose you are a British venture capitalist holding a major stake in an e
-
commerce start
-
up in Silicon Valiey. As a British resident, you are concerned with the pound value of your U
.
S
.
equity position. Assume that if the American economy booms in the future, your equity stake will be worth $
1
,
0
0
0
,
0
0
0
,
and the exchange rate will be $
1
,
4
0
per pound. If the American economy experiences a recession, on the other hand, your American equity stake will be worth $
5
0
0
,
0
0
0
,
and the exchange rate will be $
1
.
6
0
per pound. You assess that the American economy will experience a boom with a
7
0
percent probability and a recession with a
3
0
percent probability.
Required:
a
.
Estimate your exposure to the exchange risk.
b
.
Compute the variance of the pound value of your American equity position that is attributable to the exchange rate uncertainty.
c
-
1
.
How would you hedge this exposure?
c
-
2
.
If you hedge, what is the variance of the pound value of the hedged position?
Answer is not complete.
Complete this question by entering your answers in the tabs below.
◻
◻
◻
Required C
2
If you hedge, what is the variance of the pound value of the hedged position?
Note: Do not round intermediate calculations. Round final answer to nearest dollar.
\
table
[
[
Variance
,
0
0
]
]i 3 i
ARLE i]
fv § bi Ih
HIER
HRA
Gilli Hil
ga] in qi
HRRIEES
| i
PH
i jl
fas
Question:
Hide student question
Time Left :
01
:
54
:
45
Student question
Suppose you are a British venture capitalist holding a major stake in an e
-
commerce start
-
up in Silicon Valiey. As a British resident, you are concerned with the pound value of your U
.
S
.
equity position. Assume that if the American economy booms in the future, your equity stake will be worth $
1
,
0
0
0
,
0
0
0
,
and the exchange rate will be $
1
,
4
0
per pound. If the American economy experiences a recession, on the other hand, your American equity stake will be worth $
5
0
0
,
0
0
0
,
and the exchange rate will be $
1
.
6
0
per pound. You assess that the American economy will experience a boom with a
7
0
percent probability and a recession with a
3
0
percent probability.
Required:
a
.
Estimate your exposure to the exchange risk.
b
.
Compute the variance of the pound value of your American equity position that is attributable to the exchange rate uncertainty.
c
-
1
.
How would you hedge this exposure?
c
-
2
.
If you hedge, what is the variance of the pound value of the hedged position?
Answer is not complete.
Complete this question by entering your answers in the tabs below.
◻
◻
◻
Required C
2
If you hedge, what is the variance of the pound value of the hedged position?
Note: Do not round intermediate calculations. Round final answer to nearest dollar.
\
table
[
[
Variance
,
0
0
]
]i 3 i
ARLE i]
fv § bi Ih
HIER
HRA
Gilli Hil
ga] in qi
HRRIEES
| i
PH
i jl
fas
This is AI generated Response.
Asked by: Kota Swarupa Rani
Created at: 2025-07-20 08:57:42
Final Answer:
RenderedRaw Text
Did you like this answer?
Certainly! Let's **complete Required C-2** from your question:
### Required C-2:
**If you hedge, what is the variance of the pound value of the hedged position?**
---
#### **Analysis**
When you hedge perfectly (e.g., by locking in the forward rate or using a forward contract), you eliminate all exchange rate risk.
This means the only risk that remains is from the value of your dollar equity position itself (not from currency movements).
But if you hedge both the currency and the dollar value (which is only possible in theory), the variance becomes **0**.
However, in most cases, a hedge against currency risk alone will leave only the dollar-value risk (but the question asks specifically about variance "attributable to the exchange rate uncertainty" and after hedging).
##### **In this case:**
- **A perfect currency hedge** means the pound value of your U.S. equity stake is fixed at the forward rate, so **exchange rate risk is eliminated**.
- The variance in the pound value due to currency movements is now **0**.
---
### **Final Answer (rounded to nearest dollar):**
| Variance |
|----------|
| 0 |
---
**Explanation:**
By hedging, you eliminate all the variance in the pound value of your equity stake that is attributable to exchange rate movements. Thus, the answer is **0**.
Let me know if you need help with the prior parts or want to see the calculations for the unhedged variance!
Question:
I want step by step a, b, c Calculation formulas summery
This is AI generated Response.
Asked by: Kota Swarupa Rani
Created at: 2025-07-20 09:01:58
Final Answer:
RenderedRaw Text
Did you like this answer?
Certainly! Here's a step-by-step summary of the calculation formulas for parts a, b, and c of your problem:
---
### **Part a: Estimate your exposure to exchange risk**
**Objective:** Find the expected pound value of your equity, considering the possible future states and their probabilities.
**Given:**
- Boom probability \( p_b = 0.7 \)
- Recession probability \( p_r = 0.3 \)
**Future values:**
- Boom: Equity worth = \$1,000,000; Exchange rate = \$1.40/£
- Recession: Equity worth = \$500,000; Exchange rate = \$1.60/£
**Pound value in each state:**
- Boom: \( PV_b = \frac{\$1,000,000}{\$1.40} \)
- Recession: \( PV_r = \frac{\$500,000}{\$1.60} \)
**Expected pound value (exposure):**
\[
E[\text{Pound Value}] = p_b \times PV_b + p_r \times PV_r
\]
---
### **Part b: Compute the variance of the pound value attributable to exchange rate uncertainty**
**Objective:** Measure the variability of pound value due to exchange rate fluctuations.
**Steps:**
1. Calculate the pound values in each state (as above).
2. Compute the expected pound value \( \mu \) (from part a).
3. Use the variance formula:
\[
\text{Var} = p_b \times (PV_b - \mu)^2 + p_r \times (PV_r - \mu)^2
\]
---
### **Part c-1: How would you hedge this exposure?**
**Objective:** To eliminate exchange rate risk, you can use a forward contract or other derivatives to lock in the exchange rate at a known rate (e.g., the current forward rate).
**Method:**
- Enter into a forward contract to sell the future dollar amount at a fixed rate, ensuring the pound value is fixed regardless of future exchange rate movements.
---
### **Part c-2: Variance of the pound value after hedging**
**Objective:** Determine the remaining variability after perfect hedging.
**Result:**
- A perfect hedge eliminates exchange rate risk, so the variance attributable to exchange rate fluctuations becomes **zero**.
\[
\boxed{
\text{Variance after hedge} = 0
}
\]
---
### **Summary of formulas:**
| Part | Formula / Description |
|--------|-------------------------|
| a | \( E[\text{Pound Value}] = p_b \times \frac{\$1,000,000}{\$1.40} + p_r \times \frac{\$500,000}{\$1.60} \) |
| b | \( \text{Var} = p_b \times \left( \frac{\$1,000,000}{\$1.40} - \mu \right)^2 + p_r \times \left( \frac{\$500,000}{\$1.60} - \mu \right)^2 \) where \( \mu \) is the expected pound value from part a |
| c-1 | Hedge using a forward contract or similar instruments to fix the exchange rate |
| c-2 | Variance after hedge \( = 0 \) (since exchange rate risk is eliminated) |
---
If you'd like, I can also help you perform the actual numerical calculations based on these formulas!
Question:
Yes i want each and every
This is AI generated Response.
Asked by: Kota Swarupa Rani
Created at: 2025-07-20 09:09:36
Final Answer:
RenderedRaw Text
Did you like this answer?
Certainly! Let's go through each part step-by-step with detailed calculations.
---
## Part a: Estimate your exposure to exchange risk
### Given Data:
- **Probability of boom** \( p_b = 0.7 \)
- **Probability of recession** \( p_r = 0.3 \)
### Future values:
- **Boom:**
- U.S. equity value: \$1,000,000
- Exchange rate: \$1.40/£
- Pound value: \( PV_b = \frac{\$1,000,000}{\$1.40} = 714,285.71 \text{ pounds} \)
- **Recession:**
- U.S. equity value: \$500,000
- Exchange rate: \$1.60/£
- Pound value: \( PV_r = \frac{\$500,000}{\$1.60} = 312,500 \text{ pounds} \)
### Expected pound value:
\[
E[\text{Pound value}] = p_b \times PV_b + p_r \times PV_r
\]
\[
= 0.7 \times 714,285.71 + 0.3 \times 312,500
\]
\[
= 0.7 \times 714,285.71 = 500,000
\]
\[
= 0.3 \times 312,500 = 93,750
\]
**Total expected pound value:**
\[
\boxed{
\textbf{Approximately } \textbf{\$593,750}
}
\]
---
## Part b: Compute the variance attributable to exchange rate uncertainty
### Step 1: Calculate deviations from the mean:
- \( PV_b = 714,285.71 \) pounds
- \( PV_r = 312,500 \) pounds
- \( \mu = 593,750 \) pounds (from part a)
### Step 2: Variance formula:
\[
\text{Var} = p_b \times (PV_b - \mu)^2 + p_r \times (PV_r - \mu)^2
\]
Calculate deviations:
- \( PV_b - \mu = 714,285.71 - 593,750 = 120,535.71 \)
- \( PV_r - \mu = 312,500 - 593,750 = -281,250 \)
### Step 3: Square deviations:
- \( (120,535.71)^2 \approx 1.452 \times 10^{10} \)
- \( (-281,250)^2 \approx 7.911 \times 10^{10} \)
### Step 4: Apply probabilities:
\[
\text{Variance} = 0.7 \times 1.452 \times 10^{10} + 0.3 \times 7.911 \times 10^{10}
\]
\[
= (0.7 \times 1.452 \times 10^{10}) + (0.3 \times 7.911 \times 10^{10})
\]
\[
= 1.016 \times 10^{10} + 2.373 \times 10^{10} = 3.389 \times 10^{10}
\]
### Final answer for **Part b:**
\[
\boxed{
\text{Variance} \approx 33,890,000,000 \text{ (dollars squared)}
}
\]
*Note:* Since the pound values are large, the variance is also large. When reporting, you would typically keep it as is or convert to a more interpretable form.
---
## Part c-1: How would you hedge this exposure?
**Answer:**
To hedge, you would enter into a **forward contract** to lock in the exchange rate at a fixed rate (e.g., the current forward rate or an agreed-upon rate). This ensures that regardless of future exchange rate movements, the pound value of your U.S. equity remains constant, effectively eliminating the exchange risk.
---
## Part c-2: Variance of the pound value after hedging
**Answer:**
A **perfect hedge** removes all exchange rate risk, so the **variance attributable to exchange rate fluctuations becomes zero**.
\[
\boxed{
\text{Variance after hedge} = 0
}
\]
---
## **Summary:**
| Part | Calculation / Result |
|--------|-------------------------|
| **a** | Expected pound value: \(\$593,750\) |
| **b** | Variance: \(\approx 33,890,000,000\) dollars squared |
| **c-1** | Hedge with a forward contract to lock exchange rate |
| **c-2** | Variance after hedging: **0** |
---
If you'd like, I can help you interpret these results further or assist with any additional questions!
VIPSolutions focuses on clear, step‑by‑step explanations so you can learn quickly. Whether you need an AI‑generated walkthrough or a short hint to get unstuck, each solution is organized for fast reading and easy review later.
Search similar questions, compare approaches, and bookmark the best answers for revision. Our goal is simple: quick, reliable study help that feels natural—not noisy.
 VIPSolutions
 i 3 i
ARLE i]
fv § bi Ih
HIER
HRA
Gilli Hil
ga] in qi
HRRIEES
| i
PH
i jl
fas