Give step-by-step solution with explanation and final answer:P5. Flyer Corporation manufactures two products, Product A
and Product B. Product B is of fairly recent origin, having been
developed as an attempt to enter a market closely related to that
of Product A. Product B is the more complex of the two
products, requiring three hours of direct labor time per unit to
manufacture compared to one and one-half hours of direct labor
time for Product A. Product B is produced on an automated
production line.
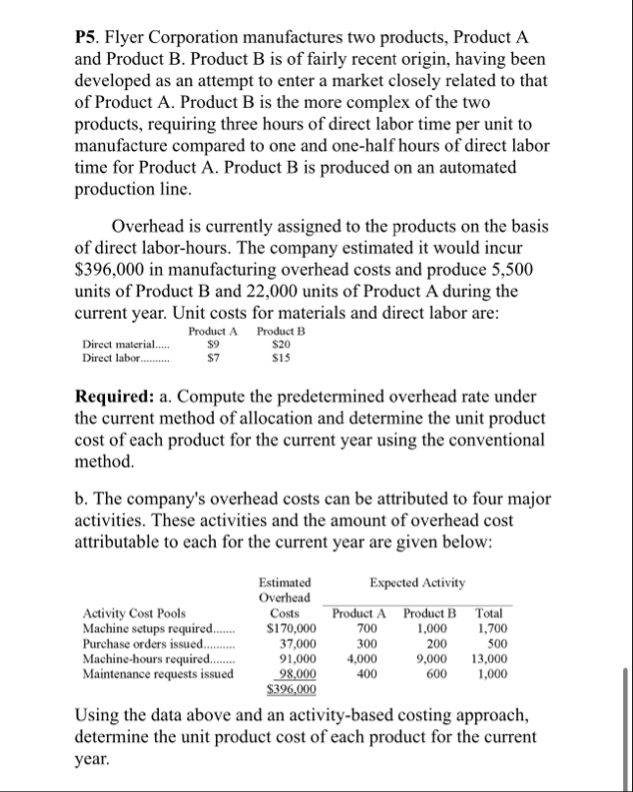
Overhead is currently assigned to the products on the basis
of direct labor-hours. The company estimated it would incur
$396,000 in manufacturing overhead costs and produce 5.500
units of Product B and 22,000 units of Product A during the
current year. Unit costs for materials and direct labor are:
Product A Product B
Direct material 59 s20
Direct labor. 7 sis
Required: a. Compute the predetermined overhead rate under
the current method of allocation and determine the unit product
cost of each product for the current year using the conventional
method.
b. The company's overhead costs can be attributed to four major
activities. These activities and the amount of overhead cost
attributable to each for the current year are given below:
Estimated Expected Activity
Overhead
Activity Cost Pools Costs. Product A Product B Total
Machine setups required. $170,000 700 1000 1,700
Purchase orders issued. 37000 300 200 500
Machine-hours required. 91000 4000 9000 13.000
Maintenance requests issued 98000 400 600 1,00
$396,000
Using the data above and an activity-based costing approach,
determine the unit product cost of each product for the current
year.
Question:
Give step-by-step solution with explanation and final answer:P5. Flyer Corporation manufactures two products, Product A
and Product B. Product B is of fairly recent origin, having been
developed as an attempt to enter a market closely related to that
of Product A. Product B is the more complex of the two
products, requiring three hours of direct labor time per unit to
manufacture compared to one and one-half hours of direct labor
time for Product A. Product B is produced on an automated
production line.
Overhead is currently assigned to the products on the basis
of direct labor-hours. The company estimated it would incur
$396,000 in manufacturing overhead costs and produce 5.500
units of Product B and 22,000 units of Product A during the
current year. Unit costs for materials and direct labor are:
Product A Product B
Direct material 59 s20
Direct labor. 7 sis
Required: a. Compute the predetermined overhead rate under
the current method of allocation and determine the unit product
cost of each product for the current year using the conventional
method.
b. The company's overhead costs can be attributed to four major
activities. These activities and the amount of overhead cost
attributable to each for the current year are given below:
Estimated Expected Activity
Overhead
Activity Cost Pools Costs. Product A Product B Total
Machine setups required. $170,000 700 1000 1,700
Purchase orders issued. 37000 300 200 500
Machine-hours required. 91000 4000 9000 13.000
Maintenance requests issued 98000 400 600 1,00
$396,000
Using the data above and an activity-based costing approach,
determine the unit product cost of each product for the current
year.
This is AI generated Response.
Asked by: Shikhar
Created at: 2025-10-04 21:49:24
Final Answer:
RenderedRaw Text
Did you like this answer?
Let's break down the step by step both requirements (a) and (b):
---
## **a. ConventionalDirect Labor-Hour) Method**
**Step 1: Calculate Total Direct Labor-Hours**
- **Product A:**
\( 22,000 \text{ units} \times 1.5 \text{ hours/unit} = 33,000 \text{ hours} \)
- **Product B:**
\( 5,500 \text{ units} \times 3 \text{ hours/unit} = 16,500 \text{ hours} \)
- **Total Direct Labor-Hours:**
\( 33,000 + 16,500 = 49,500 \text{ hours} \)
---
### **Step 2: Calculate Predetermined Overhead Rate**
\[
\text{Overhead Rate} = \frac{\text{Total Estimated Overhead}}{\text{Total Direct Labor-Hours}}
= \frac{\$396,000}{49,500 \text{ hours}}
= \$8/\text{DLH}
\]
---
### **Step 3: Allocate Overhead to Each Product**
- **Product A:**
\( 1.5 \text{ hours/unit} \times \$8 = \$12 \) overhead per unit
- **Product B:**
\( 3 \text{ hours/unit} \times \$8 = \$24 \) overhead per unit
---
### **Step 4: Calculate Total Unit Product Cost**
#### **Product A:**
- Direct Material: \$9
- Direct Labor: \$7
- Overhead: \$12
**Total: \$28**
#### **Product B:**
- Direct Material: \$20
- Direct Labor: \$15
- Overhead: \$24
**Total: \$59**
---
## **b. Activity-Based Costing (ABC) Method**
### **Step 1: Calculate Cost Driver Rates**
- **Machine Setups:**
\( \$170,000 / 1,700 = \$100 \) per setup
- **Purchase Orders:**
\( \$37,000 / 500 = \$74 \) per order
- **Machine-Hours:**
\( \$91,000 / 13,000 = \$7 \) per machine-hour
- **Maintenance Requests:**
\( \$98,000 / 1,000 = \$98 \) per request
---
### **Step 2: Assign Overhead to Each Product**
#### **Product A:**
- Machine Setups: \( 700 \times \$100 = \$70,000 \)
- Purchase Orders: \( 300 \times \$74 = \$22,200 \)
- Machine-Hours: \( 4,000 \times \$7 = \$28,000 \)
- Maintenance Requests: \( 400 \times \$98 = \$39,200 \)
- **Total Overhead for Product A:**
\( \$70,000 + \$22,200 + \$28,000 + \$39,200 = \$159,400 \)
- **Overhead per Unit A:**
\( \$159,400 / 22,000 = \$7.245 \approx \$7.25 \)
#### **Product B:**
- Machine Setups: \( 1,000 \times \$100 = \$100,000 \)
- Purchase Orders: \( 200 \times \$74 = \$14,800 \)
- Machine-Hours: \( 9,000 \times \$7 = \$63,000 \)
- Maintenance Requests: \( 600 \times \$98 = \$58,800 \)
- **Total Overhead for Product B:**
\( \$100,000 + \$14,800 + \$63,000 + \$58,800 = \$236,600 \)
- **Overhead per Unit B:**
\( \$236,600 / 5,500 = \$43.018 \approx \$43.02 \)
---
### **Step 3: Calculate Total Unit Product Cost (ABC)**
#### **Product A:**
- Direct Material: \$9
- Direct Labor: \$7
- Overhead: \$7.25
**Total: \$23.25**
#### **Product B:**
- Direct Material: \$20
- Direct Labor: \$15
- Overhead: \$43.02
**Total: \$78.02**
---
## **Summary Table**
| Product | Method | Direct Material | Direct Labor | Overhead | Total Unit Cost |
|-----------|---------------|----------------|--------------|----------|-----------------|
| Product A | Conventional | $9 | $7 | $12 | $28.00 |
| Product B | Conventional | $20 | $15 | $24 | $59.00 |
| Product A | ABC | $9 | $7 | $7.25 | $23.25 |
| Product B | ABC | $20 | $15 | $43.02 | $78.02 |
---
### **Final Answers**
- **Conventional Method:**
- Product A: **\$28.00** per unit
- Product B: **\$59.00** per unit
- **ABC Method:**
- Product A: **\$23.25** per unit
- Product B: **\$78.02** per unit
Let me know if you need a breakdown of calculations or further explanation on any step!
Question:
explain theory part for each calculateion
This is AI generated Response.
Asked by: Shikhar
Created at: 2025-10-04 21:51:20
Final Answer:
RenderedRaw Text
Did you like this answer?
# Theory Behind Each Calculation
Understanding the calculation methods used in cost accounting is essential for evaluating product costs accurately. Below is a theoretical overview of the two methods used: the Conventional Method (Direct Labor-Hour) and the Activity-Based Costing (ABC) Method.
## **1. Conventional Method (Direct Labor-Hour)**
### **Overview**
This method allocates manufacturing overhead costs based on direct labor hours. This approach assumes that the amount of overhead incurred is directly proportional to the labor hours worked.
### **Key Steps Explained**
#### **Step 1: Total Direct Labor-Hours**
- **Calculation:** Multiply the units produced by hours required per unit.
- **Theory:** This step provides the total time laborers spend on manufacturing, forming the basis for overhead allocation.
#### **Step 2: Predetermined Overhead Rate**
- **Calculation:** Divide total estimated overhead costs by total direct labor hours.
- **Theory:** The overhead rate reflects the cost incurred for every hour of labor used in production. This rate is predetermined to facilitate budget planning.
#### **Step 3: Allocate Overhead**
- **Calculation:** Multiply the overhead rate by the direct labor hours for each product.
- **Theory:** This allocation method ensures that each product bears a fair share of the overhead costs based on its labor intensity.
#### **Step 4: Total Unit Product Cost**
- **Calculation:** Sum direct materials, direct labor, and allocated overhead.
- **Theory:** This step gives the total cost of producing one unit, which is vital for pricing strategies and profitability analysis.
## **2. Activity-Based Costing (ABC) Method**
### **Overview**
ABC assigns overhead costs based on activities that consume resources, providing a more accurate cost per product by identifying the relationship between costs, activities, and products.
### **Key Steps Explained**
#### **Step 1: Cost Driver Rates**
- **Calculation:** Divide the total cost for each activity by the total number of cost drivers (like setups, orders, etc.).
- **Theory:** This approach recognizes that not all products consume resources equally. It assigns costs based on actual usage of activities.
#### **Step 2: Assign Overhead**
- **Calculation:** Multiply the cost driver rate by the number of cost drivers for each product.
- **Theory:** This step provides a more precise allocation of overhead based on specific activities related to each product. It highlights the complexity of production processes.
#### **Step 3: Total Unit Product Cost**
- **Calculation:** Add direct materials, direct labor, and allocated overhead from ABC.
- **Theory:** The total cost reflects a more accurate picture of production costs by considering the activities that drive costs, leading to better decision-making in pricing and efficiency improvements.
## **Conclusion**
Each method offers unique insights into cost management. The Conventional Method is simpler and easier to implement but may not reflect the true cost of production as accurately as the ABC method. ABC provides detailed insights into cost behavior and resource usage, which can inform strategic decisions about product pricing and resource allocation. Understanding these methods allows managers to choose the most appropriate costing approach based on their organizational needs.
VIPSolutions focuses on clear, step‑by‑step explanations so you can learn quickly. Whether you need an AI‑generated walkthrough or a short hint to get unstuck, each solution is organized for fast reading and easy review later.
Search similar questions, compare approaches, and bookmark the best answers for revision. Our goal is simple: quick, reliable study help that feels natural—not noisy.
 VIPSolutions
 P5. Flyer Corporation manufactures two products, Product A
and Product B. Product B is of fairly recent origin, having been
developed as an attempt to enter a market closely related to that
of Product A. Product B is the more complex of the two
products, requiring three hours of direct labor time per unit to
manufacture compared to one and one-half hours of direct labor
time for Product A. Product B is produced on an automated
production line.
Overhead is currently assigned to the products on the basis
of direct labor-hours. The company estimated it would incur
$396,000 in manufacturing overhead costs and produce 5.500
units of Product B and 22,000 units of Product A during the
current year. Unit costs for materials and direct labor are:
Product A Product B
Direct material 59 s20
Direct labor. 7 sis
Required: a. Compute the predetermined overhead rate under
the current method of allocation and determine the unit product
cost of each product for the current year using the conventional
method.
b. The company's overhead costs can be attributed to four major
activities. These activities and the amount of overhead cost
attributable to each for the current year are given below:
Estimated Expected Activity
Overhead
Activity Cost Pools Costs. Product A Product B Total
Machine setups required. $170,000 700 1000 1,700
Purchase orders issued. 37000 300 200 500
Machine-hours required. 91000 4000 9000 13.000
Maintenance requests issued 98000 400 600 1,00
$396,000
Using the data above and an activity-based costing approach,
determine the unit product cost of each product for the current
year.