 VIPSolutions
Give step-by-step solution with explanation and final answer:Suppose X and Y are independent random variables having the same Poisson distribution with parameter A, but where 1 is also random, being exponentially distributed with parameter 8 . What is the conditional distribution for X given that X +Y =n?
Question:
Give step-by-step solution with explanation and final answer: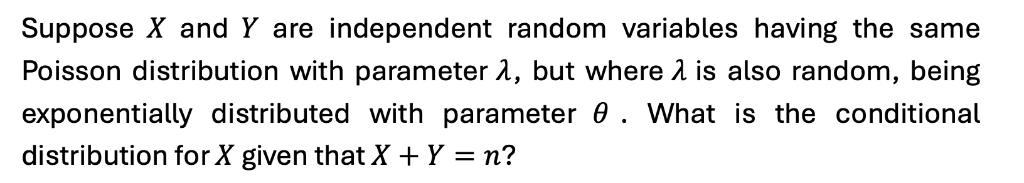 Suppose X and Y are independent random variables having the same
Poisson distribution with parameter A, but where 1 is also random, being
exponentially distributed with parameter 8 . What is the conditional
distribution for X given that X +Y =n?
This is AI generated Response.
Asked by: venkatesh
Created at: 2025-09-29 18:10:47
Asked by: venkatesh
Created at: 2025-09-29 18:10:47
Final Answer:
Rendered
Raw Text
Did you like this answer?
Let's break down and solve the problem step by step.
---
## **Step 1: Understanding the Problem**
- \( X \) and \( Y \) are independent, given \(\lambda\).
- \( X | \lambda \sim \text{Poisson}(\lambda) \)
- \( Y | \lambda \sim \text{Poisson}(\lambda) \)
- \(\lambda \sim \text{Exp}(\theta)\), i.e., \( f_\lambda(\lambda) = \theta e^{-\theta \lambda} \) for \( \lambda \geq \).
- We seek the conditional distribution of \( X \mid (X+Y = n) \).
---
## **Step 2: Joint Distribution**
The joint pmf of \( (X, Y, \lambda) \) is:
\[
P(X = x, Y = y, \lambda) = P(X = x | \lambda) P(Y = y | \lambda) f_\lambda(\lambda)
\]
- \( P(X = x | \lambda) = \frac{\lambda^x e^{-\lambda}}{x!} \)
- \( P(Y = y | \lambda) = \frac{\lambda^y e^{-\lambda}}{y!} \)
- \( f_\lambda(\lambda) = \theta e^{-\theta\lambda} \)
So,
\[
P(X = x, Y = y, \lambda) = \frac{\lambda^x}{x!} e^{-\lambda} \cdot \frac{\lambda^y}{y!} e^{-\lambda} \cdot \theta e^{-\theta\lambda}
= \frac{\lambda^{x+y}}{x!y!} e^{-2\lambda} \theta e^{-\theta\lambda}
\]
\[
= \frac{\lambda^{x+y}}{x!y!} \theta e^{-(\theta+2)\lambda}
\]
---
## **Step 3: Marginal for \(X, Y\)**
Integrate out \(\lambda\):
\[
P(X = x, Y = y)
= \int_^\infty \frac{\lambda^{x+y}}{x!y!} \theta e^{-(\theta+2)\lambda} d\lambda
\]
This integral is of the form:
\[
\int_^\infty \lambda^k e^{-a\lambda} d\lambda = \frac{\Gamma(k+1)}{a^{k+1}}
\]
Here, \(k = x+y\), \(a = \theta+2\).
\[
P(X = x, Y = y) = \frac{\theta}{x!y!} \frac{\Gamma(x+y+1)}{(\theta+2)^{x+y+1}}
\]
But \(\Gamma(x+y+1) = (x+y)!\):
\[
P(X = x, Y = y) = \frac{\theta (x+y)!}{x!y! (\theta+2)^{x+y+1}}
\]
---
## **Step 4: Conditional Distribution \(P(X = k | X+Y = n)\)**
Let \(X = k\), \(Y = n-k\):
\[
P(X = k | X+Y = n) = \frac{P(X = k, Y = n-k)}{P(X+Y = n)}
\]
- Numerator: \(P(X = k, Y = n-k) = \frac{\theta n!}{k! (n-k)! (\theta+2)^{n+1}}\)
- Denominator: \(P(X+Y = n) = \sum_{j=}^n P(X = j, Y = n-j)\)
\[
= \sum_{j=}^n \frac{\theta n!}{j! (n-j)! (\theta+2)^{n+1}}
= \frac{\theta n!}{(\theta+2)^{n+1}} \sum_{j=}^n \frac{1}{j!(n-j)!}
= \frac{\theta n!}{(\theta+2)^{n+1}} \cdot \frac{2^n}{n!}
= \frac{\theta 2^n}{(\theta+2)^{n+1}}
\]
---
## **Step 5: Simplify the Conditional Probability**
\[
P(X = k | X+Y = n) = \frac{\frac{\theta n!}{k! (n-k)! (\theta+2)^{n+1}}}{\frac{\theta 2^n}{(\theta+2)^{n+1}}}
= \frac{n!}{k! (n-k)!} \cdot \frac{1}{2^n}
\]
\[
= \binom{n}{k} \frac{1}{2^n}
\]
---
## **Step 6: Final Answer**
The conditional distribution is:
\[
\boxed{X \mid (X+Y = n) \sim \text{Binomial}(n, 1/2)}
\]
That is,
\[
P(X = k \mid X+Y = n) = \binom{n}{k} \frac{1}{2^n}
\]
---
### **Explanation**
Even though \(X\) and \(Y\) are not independent marginally (because they share the random \(\lambda\)), conditioning on their sum removes the effect of \(\lambda\), and the distribution is symmetric in \(X\) and \(Y\), just as in the fixed-\(\lambda\) case. Thus, the answer is a binomial distribution with probability \(1/2\).
📢 Instructions:
- Ask anything relatd to above question only.
- For new Question goto :