Give step-by-step solution with explanation and final answer:Imagine you have the following table of credit spreads for corporate
bonds with 10 years to maturity:
Credit Spread (above risk-free
Rating rate)
hp | os
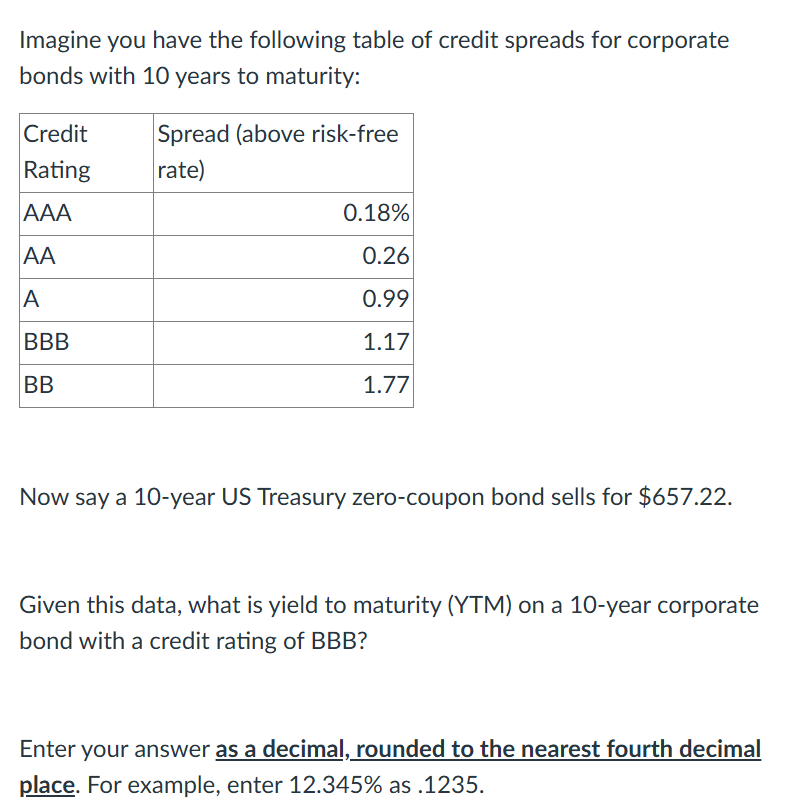
Now say a 10-year US Treasury zero-coupon bond sells for $657.22.
Given this data, what is yield to maturity (YTM) on a 10-year corporate
bond with a credit rating of BBB?
Enter your answer as a decimal, rounded to the nearest fourth decimal
place. For example, enter 12.345% as .1235.
Question:
Give step-by-step solution with explanation and final answer:Imagine you have the following table of credit spreads for corporate
bonds with 10 years to maturity:
Credit Spread (above risk-free
Rating rate)
hp | os
Now say a 10-year US Treasury zero-coupon bond sells for $657.22.
Given this data, what is yield to maturity (YTM) on a 10-year corporate
bond with a credit rating of BBB?
Enter your answer as a decimal, rounded to the nearest fourth decimal
place. For example, enter 12.345% as .1235.
This is AI generated Response.
Asked by: RAJESH POTHALA
Created at: 2025-09-18 21:03:40
Final Answer:
RenderedRaw Text
Did you like this answer?
## Step-by-Step Solution
### **Step 1: Find the Yield to Maturity (YTM) of the Treasury Bond (Risk-Free Rate)**
A 10-year **zero-coupon** Treasury bond sells for **$657.22**. Zero-coupon means it pays no interest, just face value at maturity.
Let the face value \( F \) be **$1,000** (standard assumption unless otherwise stated).
The formula for zero-coupon bond price:
\[
P = \frac{F}{(1 + r)^n}
\]
Where:
- \( P = 657.22 \)
- \( F = 1000 \)
- \( n = 10 \)
- \( r = \) risk-free rate (YTM)
\[
657.22 = \frac{1000}{(1 + r)^{10}}
\]
Rearrange and solve for \( r \):
\[
(1 + r)^{10} = \frac{1000}{657.22}
\]
\[
(1 + r)^{10} = 1.521
\]
\[
1 + r = (1.521)^{1/10}
\]
\[
1 + r = 1.0432
\]
\[
r = 0.0432
\]
So, the **risk-free rate** is **0.0432** (or 4.32%).
---
### **Step 2: Add the Credit Spread for BBB Bonds**
From the table:
- **BBB spread = 1.17% = 0.0117**
The YTM for a 10-year BBB corporate bond:
\[
\text{YTM}_{\text{BBB}} = \text{risk-free rate} + \text{credit spread}
\]
\[
\text{YTM}_{\text{BBB}} = 0.0432 + 0.0117 = 0.0549
\]
---
### **Step 3: Final Answer**
\[
\boxed{0.0549}
\]
---
#### **Summary**
- **Risk-free YTM (Treasury):** 0.0432
- **BBB spread:** 0.0117
- **BBB Bond YTM:** **0.0549** (as a decimal, rounded to four places)
Question:
Now give this answer completely without skipping even a small step of calculation and try not to give answer in long paragraphs and answer the questions by following these instructions:
?Solution should be in proper format.
?A complete answer starts with the problem's objective OR addition of available data/ information Or the right approach.
?Add all necessary steps/supporting explanations until the answer is complete.
?If there are any formulae, you should mention it.
?Write calculations in a format so it can be easily pasted in chegg equation render tool.
?Do not use Python or any code-based for calculations (Important).
?Double check the solution to accomplish the correct concept, explanation, and calculations before submitting.
✅ The Final Answer should be a simple and clear summary of the solution in lucid language.
✅ The Final Answer Step is to include the crux of the entire solution.
✅ The final answer step contains the result of the solution only in a clear & concise manner.
✅ The Final Answer should be a simple and clear summary of the solution in lucid language.
✅ Final Answer Step is to include the crux of the entire solution.
✅Final answer step contains the result of the solution only in clear & concise manner.
This is AI generated Response.
Asked by: RAJESH POTHALA
Created at: 2025-09-18 21:25:26
Final Answer:
RenderedRaw Text
Did you like this answer?
# Calculation of Yield to Maturity (YTM) for a 10-Year BBB Corporate Bond
## Objective
To determine the yield to maturity (YTM) of a 10-year corporate bond rated BBB, using the price of a 10-year U.S. Treasury zero-coupon bond and its associated credit spread.
## Given Data
- Price of 10-year Treasury zero-coupon bond, \( P = 657.22 \)
- Face value of Treasury bond, \( F = 1000 \)
- Maturity, \( n = 10 \) years
- Credit spread for BBB bonds, \( \text{spread} = 1.17\% = 0.0117 \)
## Step 1: Calculate the Risk-Free Rate (YTM of Treasury Bond)
Using the formula for a zero-coupon bond:
\[
P = \frac{F}{(1 + r)^n}
\]
Substituting the known values:
\[
657.22 = \frac{1000}{(1 + r)^{10}}
\]
Rearranging the equation:
\[
(1 + r)^{10} = \frac{1000}{657.22}
\]
Calculating the right side:
\[
(1 + r)^{10} = 1.521
\]
Taking the tenth root:
\[
1 + r = (1.521)^{1/10}
\]
Calculating the root:
\[
1 + r \approx 1.0432
\]
Solving for \( r \):
\[
r \approx 1.0432 - 1 = 0.0432
\]
Thus, the risk-free rate is:
\[
\text{risk-free rate} = 0.0432 \quad \text{(or 4.32\%)}
\]
## Step 2: Calculate the YTM for BBB Corporate Bond
The YTM for a corporate bond can be calculated as:
\[
\text{YTM}_{\text{BBB}} = \text{risk-free rate} + \text{credit spread}
\]
Substituting the values:
\[
\text{YTM}_{\text{BBB}} = 0.0432 + 0.0117
\]
Calculating the YTM:
\[
\text{YTM}_{\text{BBB}} = 0.0549
\]
## Final Answer
The yield to maturity (YTM) for the 10-year corporate bond with a BBB rating is:
\[
\boxed{0.0549}
\]
Question:
2)Updated Calculations Question Prompt:
1: Introduction:
Provide the complete necessary conceptual background concepts explanation and the
introduction required to understand and answer the given question. Add an Explanation
block at the end of the introduction by adding various relevant supporting statements and
explaining the introduction concisely.
Note: Do not use personal pronouns like I, we, you, etc. The response must look as if it is
written by a human.
Explanation: Articulate the importance of the introduction, providing more relevant
comprehensive supporting statements that link these concepts directly to the question.
This explanation should clarify how the introduction aids in comprehending the
subsequent steps.
2: Presentation of Relevant Formulas Required To Solve The Question:
List and also describe all formulas required to solve the question. Ensure each formula is
presented clearly and is directly applicable to the problem.
Explanation: Detail the derivation or rationale behind each formula, explaining its
relevance and necessity in the context of the problem-solving process. Use more relavent
comprehensive supporting statements to reinforce the significance of these mathematical
tools.
3: A Detailed Step-by-Step Solution:
Write a step-by-step in-depth comprehensive straight forward complete solution in a
structured way without missing anything as per the requirements and also include
explanation [ Write relevant supporting statements in the explanation block ] for every step
in the solution.
Conclusion:
Conclude with a concise summary of the solution, succinctly presenting the final answer
short summary derived from the calculations.
Follow These Guidelines While Answering The Question:
1. Maintain a professional and impersonal tone throughout, avoiding personal
pronouns such as 'I', 'we', 'you', etc.
2. Ensure more accuracy and adherence to the necessary concepts and correct
textbook based correct formulas and other relevant, required to solve the question.
3. Include an Explanation block at the end of each step to provide context and clarify
the methodology used by providing the necessary supporting statements.
4. Focus solely on delivering a well-explained direct and complete answer to the
question, without additional guidance [ I don’t need any guidance of how to solve
the question – I just need well-explained complete solution ] or extraneous content.
5. Make sure that strictly follow the specified format, ensuring that each section,
especially the introduction and each step of the solution, is accompanied by a
detailed relevant supporting statement in the explanation.
6. I need the exact detailed comprehensive direct step-by-step answer as I don’t need
any guidance to write the answer and strictly add the explanation for each with the
required supporting statement & Please give me the complete answer as per the
question requirements without skipping anything in the answer.
7. Always provide correct, complete detailed & well-explained solution.
8. Ensure that there are no typo/formula/calculation/programming/grammatical errors
are present in your solution.
9. Give the correct graphs/diagrams/tables/charts whenever required in the solution.
10. Ensure that there are NO Errors in Units/Notations are there in your solution.
11. Avoid missing any vital part in the solution [ Don’t miss any part in the solution ].
This is AI generated Response.
Asked by: RAJESH POTHALA
Created at: 2025-09-18 21:29:43
Final Answer:
RenderedRaw Text
Did you like this answer?
# Calculation of Yield to Maturity (YTM) for a 10-Year BBB Corporate Bond
## Introduction
The calculation of yield to maturity (YTM) for a corporate bond involves understanding the relationship between bond prices, interest rates, and credit risk. In this scenario, a 10-year U.S. Treasury zero-coupon bond price is given, from which the risk-free rate can be derived. This rate serves as the basis for calculating the YTM of a corporate bond with a specific credit rating (BBB). The YTM incorporates the additional risk premium associated with the bond's credit spread compared to risk-free securities.
**Explanation:**
This introduction sets the stage for understanding the significance of YTM in evaluating bond investments. The risk-free rate derived from Treasury bonds reflects the return investors expect from a secure investment, while the credit spread reflects the additional yield required for taking on additional risk associated with corporate bonds. This foundational knowledge is crucial for accurately determining the YTM of a BBB-rated bond.
## Relevant Formulas
1. **Price of a Zero-Coupon Bond:**
\[
P = \frac{F}{(1 + r)^n}
\]
- Where:
- \( P \) = Current price of the bond
- \( F \) = Face value of the bond
- \( r \) = Yield to maturity (risk-free rate)
- \( n \) = Number of years to maturity
2. **Yield to Maturity Calculation for Corporate Bond:**
\[
\text{YTM}_{\text{Corporate}} = \text{risk-free rate} + \text{credit spread}
\]
- Where:
- \(\text{YTM}_{\text{Corporate}}\) = Yield to maturity of the corporate bond
- \(\text{credit spread}\) = Additional yield demanded by investors for taking on credit risk
**Explanation:**
The first formula is critical for determining the risk-free rate from the Treasury bond price, which serves as a benchmark for all other yields. The second formula allows for the incorporation of credit risk into the YTM calculation, thus reflecting the true return expected from the corporate bond.
## Detailed Step-by-Step Solution
### Step 1: Calculate the Risk-Free Rate (YTM of the Treasury Bond)
1. Given:
- Price of Treasury bond, \( P = 657.22 \)
- Face value, \( F = 1000 \)
- Maturity, \( n = 10 \)
2. Using the zero-coupon bond formula:
\[
657.22 = \frac{1000}{(1 + r)^{10}}
\]
3. Rearranging the formula:
\[
(1 + r)^{10} = \frac{1000}{657.22}
\]
4. Calculating the right side:
\[
(1 + r)^{10} \approx 1.521
\]
5. Taking the tenth root:
\[
1 + r = (1.521)^{0.1}
\]
6. Calculating the root:
\[
1 + r \approx 1.0432
\]
7. Solving for \( r \):
\[
r \approx 1.0432 - 1 = 0.0432
\]
**Explanation:**
This step calculates the risk-free rate by rearranging the bond pricing formula. The derived risk-free rate of 0.0432 (or 4.32%) signifies the yield an investor would expect from a risk-free investment over 10 years.
### Step 2: Calculate the YTM for the BBB Corporate Bond
1. Given:
- Credit spread for BBB bonds = 1.17% = 0.0117
2. Using the YTM formula for corporate bonds:
\[
\text{YTM}_{\text{BBB}} = \text{risk-free rate} + \text{credit spread}
\]
3. Substituting the values:
\[
\text{YTM}_{\text{BBB}} = 0.0432 + 0.0117
\]
4. Calculating the YTM:
\[
\text{YTM}_{\text{BBB}} = 0.0549
\]
**Explanation:**
In this step, the YTM for the BBB corporate bond is calculated by adding the credit spread to the risk-free rate. This reflects the total expected return, accounting for the additional risk associated with the corporate bond.
## Conclusion
The calculated yield to maturity (YTM) for a 10-year corporate bond with a BBB rating is:
\[
\boxed{0.0549}
\]
This value indicates the expected return on the corporate bond, incorporating both the risk-free rate and the additional yield demanded by investors for the credit risk associated with the bond's rating.
VIPSolutions focuses on clear, step‑by‑step explanations so you can learn quickly. Whether you need an AI‑generated walkthrough or a short hint to get unstuck, each solution is organized for fast reading and easy review later.
Search similar questions, compare approaches, and bookmark the best answers for revision. Our goal is simple: quick, reliable study help that feels natural—not noisy.
 VIPSolutions
 Imagine you have the following table of credit spreads for corporate
bonds with 10 years to maturity:
Credit Spread (above risk-free
Rating rate)
hp | os
Now say a 10-year US Treasury zero-coupon bond sells for $657.22.
Given this data, what is yield to maturity (YTM) on a 10-year corporate
bond with a credit rating of BBB?
Enter your answer as a decimal, rounded to the nearest fourth decimal
place. For example, enter 12.345% as .1235.