 VIPSolutions
Give step-by-step solution with explanation and final answer:The following table gives the demand and supply schedules for widgets. Quantity Price Demanded Quantity Supplied $30 64 15 $25 76 110 $20 88 105 $15 100 100 $10 112 9% ‘The equilibrium price in this market is $_. ‘The equilibrium quantity in this market is |_| units.
Question:
Give step-by-step solution with explanation and final answer: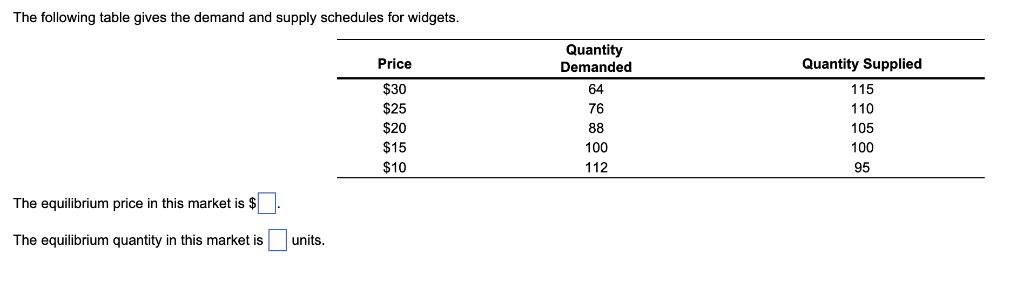 The following table gives the demand and supply schedules for widgets.
Quantity
Price Demanded Quantity Supplied
$30 64 15
$25 76 110
$20 88 105
$15 100 100
$10 112 9%
‘The equilibrium price in this market is $_.
‘The equilibrium quantity in this market is |_| units.
Asked by: Veera manikanta
Created at: 2025-09-04 03:19:59
Final Answer:
Question:
1. Introduction: Provide a comprehensive conceptual background with clear explanations required to understand and answer the given question. Include all necessary concepts and introduce them in a manner that facilitates understanding. At the end of the introduction, add an Explanation block that concisely elaborates on the introduction by adding relevant supporting statements. Explanation: Articulate the importance of the introduction by providing relevant and comprehensive supporting statements that link these concepts directly to the question. This explanation should clarify how the introduction aids in comprehending the subsequent steps. 2. Presentation of Relevant Formulas and Representation of Given Data: List and describe all formulas required to solve the question. Ensure each formula is presented clearly and is directly applicable to the problem. Also, represent all the given data systematically. Explanation: Detail the derivation or rationale behind each formula, explaining its relevance and necessity in the context of the problem-solving process. Use relevant and comprehensive supporting statements to reinforce the significance of these mathematical tools. 3. A Detailed Step-by-Step Solution: Provide a structured step-by-step solution to the given question, incorporating any relevant data provided. Include all necessary mathematical calculations presented logically and clearly. The solution must be comprehensive, addressing all aspects of the question without omission. Explanation: For each step in the solution, provide a thorough explanation of the calculations performed, including how each step contributes to solving the overall problem. Add relevant and comprehensive supporting statements to enhance understanding and connect each calculation back to the core question. Conclusion: Provide a complete, simple, and clear summary of the solution using lucid language. The conclusion should be concise yet comprehensive, encapsulating the main points, methodologies employed, and the final outcome of the solution. Ensure that the summary effectively reinforces the understanding of how the problem was addressed and how the solution resolves the question. Guidelines for Answering the Question: 1. Professional and Impersonal Tone: · Maintain a professional and impersonal tone throughout the response. · Avoid using personal pronouns such as 'I', 'we', 'you', etc. 2. Accuracy and Adherence to Concepts: · Ensure the response adheres to necessary concepts and uses correct textbook-based formulas. · Provide accurate and relevant information required to solve the question. 3. Explanation Blocks: · Include an explanation block at the end of each section or step. · Provide context and clarify the methodology used with necessary supporting statements. 4. Direct and Complete Answer: · Focus solely on delivering a well-explained, direct, and complete answer. · Avoid providing additional guidance on how to solve the question or including extraneous content. 5. Specified Format: · Follow the specified format strictly. · Ensure each section, especially the introduction and each step of the solution, is accompanied by detailed and relevant supporting statements. 6. Detailed Comprehensive Solution: · Provide an exact, detailed, and comprehensive step-by-step answer. · Include explanations for each step with the required supporting statements. 7. Correctness and Completeness: · Ensure the solution is correct, complete, and well-explained. · Avoid any errors in the solution. 8. No Errors: · Ensure there are no typographical, formulaic, calculation, programming, or grammatical errors in the solution. · Perform calculations and simplifications step-by-step vertically (downward), not horizontally (to the right side). 9. Graphs/Diagrams/Tables/Charts: · Include correct graphs, diagrams, tables, or charts whenever required in the solution. 10. Units and Notations: · Ensure there are no errors in units or notations in the solution. 11. Vital Parts: · Avoid missing any vital part of the solution. · Ensure every part of the solution is included and well-explained. I want solution in this model.
Asked by: Veera manikanta
Created at: 2025-09-04 03:21:17
Final Answer:
📢 Instructions:
- Ask anything relatd to above question only.
- For new Question goto :