 VIPSolutions
Give step-by-step solution with explanation and final answer:4. An investor is interested in purchasing a European call option on Altec, Inc., a non-dividend- paying common stock. The option has an exercise price of $15 and three months until expiration. Altec’s stock is currently trading at $14 per share and the annual standard deviation of its continuously compounded returns is 0.28. The risk-free rate of interest is 5% per year. Compute (i) the value of the call option, using the Black Scholes option pricing model; and (ii) the value of the put option basing on your answer in part (i) and the put-call parity theorem.
Question:
Give step-by-step solution with explanation and final answer: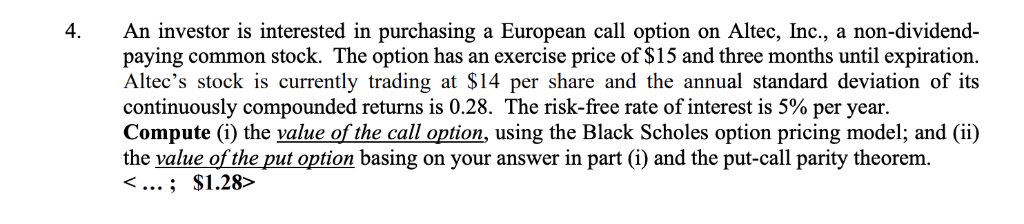 4. An investor is interested in purchasing a European call option on Altec, Inc., a non-dividend-
paying common stock. The option has an exercise price of $15 and three months until expiration.
Altec’s stock is currently trading at $14 per share and the annual standard deviation of its
continuously compounded returns is 0.28. The risk-free rate of interest is 5% per year.
Compute (i) the value of the call option, using the Black Scholes option pricing model; and (ii)
the value of the put option basing on your answer in part (i) and the put-call parity theorem.
This is AI generated Response.
Asked by: Veera manikanta
Created at: 2025-08-16 00:57:12
Asked by: Veera manikanta
Created at: 2025-08-16 00:57:12
Final Answer:
Rendered
Raw Text
Did you like this answer?
Let's solve the problem step by step:
### **Given Data**
- \( S = \$14 \) (Current stock price)
- \( K = \$15 \) (Exercise/Strike price)
- \( T = 0.25 \) years (3 months is 0.25 years)
- \( r = 0.05 \) (risk-free rate, per year)
- \( \sigma = 0.28 \) (annual standard deviation)
- No dividends.
---
### **(i) Value of the Call Option (Black-Scholes Formula)**
The Black-Scholes formula for a European call option is:
\[
C = S N(d_1) - K e^{-rT} N(d_2)
\]
Where:
\[
d_1 = \frac{\ln(S/K) + (r + \frac{1}{2}\sigma^2)T}{\sigma\sqrt{T}}
\]
\[
d_2 = d_1 - \sigma\sqrt{T}
\]
---
#### **Step 1: Calculate \(d_1\) and \(d_2\)**
First, calculate each term:
- \(\ln(S/K) = \ln(14/15) = \ln(0.9333) \approx -0.069\)
- \((r + \frac{1}{2}\sigma^2) = 0.05 + 0.5 \times (0.28^2) = 0.05 + 0.5 \times 0.0784 = 0.05 + 0.0392 = 0.0892\)
- \((r + \frac{1}{2}\sigma^2)T = 0.0892 \times 0.25 = 0.0223\)
- \(\sigma\sqrt{T} = 0.28 \times \sqrt{0.25} = 0.28 \times 0.5 = 0.14\)
Now,
\[
d_1 = \frac{-0.069 + 0.0223}{0.14} = \frac{-0.0467}{0.14} \approx -0.334
\]
\[
d_2 = -0.334 - 0.14 = -0.474
\]
---
#### **Step 2: Find \(N(d_1)\) and \(N(d_2)\)**
From the standard normal table:
- \(N(-0.334) \approx 0.369\)
- \(N(-0.474) \approx 0.317\)
---
#### **Step 3: Plug into Black-Scholes Formula**
\[
C = 14 \times 0.369 - 15 \times e^{-0.05 \times 0.25} \times 0.317
\]
First, calculate \(e^{-0.05 \times 0.25} = e^{-0.0125} \approx 0.9876\)
\[
C = 14 \times 0.369 - 15 \times 0.9876 \times 0.317
\]
\[
= 5.166 - (15 \times 0.9876 \times 0.317)
\]
\[
= 5.166 - (14.814 \times 0.317)
\]
\[
= 5.166 - 4.695
\]
\[
= 0.471
\]
**So, the value of the call option is approximately \( \boxed{0.47} \).**
---
### **(ii) Value of the Put Option (Put-Call Parity)**
Put-Call Parity:
\[
P = C + Ke^{-rT} - S
\]
Plug in the values:
- \(C = 0.47\)
- \(K = 15\)
- \(e^{-rT} = 0.9876\)
- \(S = 14\)
\[
P = 0.47 + 15 \times 0.9876 - 14
\]
\[
= 0.47 + 14.814 - 14
\]
\[
= 0.47 + 0.814
\]
\[
= 1.284
\]
**So, the value of the put option is approximately \( \boxed{1.28} \).**
---
## **Final Answers**
- **Value of Call Option:** \( \boxed{0.47} \)
- **Value of Put Option:** \( \boxed{1.28} \)
📢 Instructions:
- Ask anything relatd to above question only.
- For new Question goto :