Give step-by-step solution with explanation and final answer:
(Give me answer without using bullet-points)QUESTIQH THREE
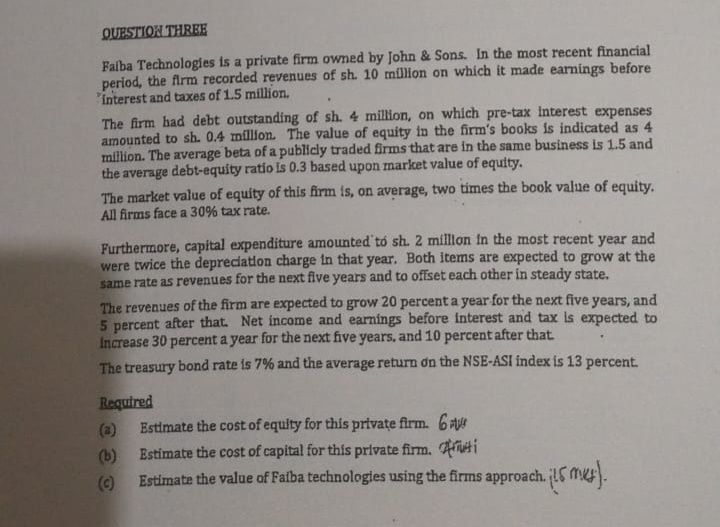
Faiba Technologies 1 a private firm owned by [ohn & Sons. I the most recent financial
period, the irm recorded revenues of sh. 10 milion on which it made eamings before,
*fnterest and taxes of LS million.
The firm had debt outstanding of sh. 4 million, on which pre-tax Interest expenses
amounted to sh. 044 million. The value of equity tn the firm's books Is indicated as 4
Tailion. The average beta of a publicly traded rms that are in the same business Is 1.5 and
the average debt-equity ratios 0.3 based upon market value of equity.
The market value of equity of this fim is, on average, two times the book value of equity.
All firms face a 30% tax rate.
capital expenditure amounted't5 sh. 2 milllon In the most recent year and
‘wice the depreciation charge in that year, Both items are expected to grow at the
rate as revenues for the next five years and to offset each other in steady state.
nutes of the firm are expected to grow 20 percenta year for the next five years, and
‘alter that. Net income and earnings before Interest and tax Is expected to
30 percent a year for the next five years, and 10 percentafier that .
bond rate {s 7% and the average return on the NSE-AS index is 13 percent.
‘Estimate the cost of equity for this private firm. £3
‘Estimate the cost of capital for this private firm. A
Estimate the value of atba technalogies sing the firms approach. L€ 14).
Question:
Give step-by-step solution with explanation and final answer:
(Give me answer without using bullet-points)QUESTIQH THREE
Faiba Technologies 1 a private firm owned by [ohn & Sons. I the most recent financial
period, the irm recorded revenues of sh. 10 milion on which it made eamings before,
*fnterest and taxes of LS million.
The firm had debt outstanding of sh. 4 million, on which pre-tax Interest expenses
amounted to sh. 044 million. The value of equity tn the firm's books Is indicated as 4
Tailion. The average beta of a publicly traded rms that are in the same business Is 1.5 and
the average debt-equity ratios 0.3 based upon market value of equity.
The market value of equity of this fim is, on average, two times the book value of equity.
All firms face a 30% tax rate.
capital expenditure amounted't5 sh. 2 milllon In the most recent year and
‘wice the depreciation charge in that year, Both items are expected to grow at the
rate as revenues for the next five years and to offset each other in steady state.
nutes of the firm are expected to grow 20 percenta year for the next five years, and
‘alter that. Net income and earnings before Interest and tax Is expected to
30 percent a year for the next five years, and 10 percentafier that .
bond rate {s 7% and the average return on the NSE-AS index is 13 percent.
‘Estimate the cost of equity for this private firm. £3
‘Estimate the cost of capital for this private firm. A
Estimate the value of atba technalogies sing the firms approach. L€ 14).
This is AI generated Response.
Asked by: Francis
Created at: 2026-01-18 20:29:44
Final Answer:
RenderedRaw Text
Did you like this answer?
Let's solve each part step by step.
---
## (a) **Estimate the Cost of Equity for this Private Firm**
**Step 1: Unlever the Beta (Remove effect of leverage from comparable firms**
Given:
- Beta of comparable listed firms (\(\beta_{L,comp}\)) = 1.5
- Average Debt/Equity ratio (D/E) = .3
- Tax rate (T) = 30%
The formula to unlever beta:
\[
\beta_U = \frac{\beta_L}{1 + (1-T)\frac{D}{E}}
\]
\[
\beta_U = \frac{1.5}{1 + (1-.3) \times .3}
\]
\[
\beta_U = \frac{1.5}{1 + .21} = \frac{1.5}{1.21} = 1.24
\]
**Step 2: Re-lever the Beta for Faiba Technologies**
Faiba's market value of equity = 2 × book value = 2 × 4 = 8 million
Debt = 4 million
D/E = 4/8 = .5
\[
\beta_{L,Faiba} = \beta_U \left[ 1 + (1-T)\frac{D}{E} \right]
\]
\[
\beta_{L,Faiba} = 1.24 \left[ 1 + (1-.3) \times .5 \right] = 1.24 [1 + .35] = 1.24 \times 1.35 = 1.674
\]
**Step 3: Calculate Cost of Equity using CAPM**
\[
Cost\ of\ Equity = R_f + \beta (R_m - R_f)
\]
Where:
- \(R_f\) (Risk-free rate) = 7%
- \(R_m\) (Market return) = 13%
- \(\beta\) = 1.674
\[
Cost\ of\ Equity = 7\% + 1.674 \times (13\% - 7\%)
\]
\[
Cost\ of\ Equity = 7\% + 1.674 \times 6\% = 7\% + 10.044\% = 17.044\%
\]
**Final Answer for (a):**
**Cost of equity = 17.04%**
---
## (b) **Estimate the Cost of Capital for this Private Firm**
**Step 1: Find Market Value Weights**
- Market value of equity = 8 million
- Debt = 4 million
- Total Value = 8 + 4 = 12 million
Weight of equity (\(w_e\)) = 8/12 = .6667
Weight of debt (\(w_d\)) = 4/12 = .3333
**Step 2: Cost of Debt After Tax**
Interest expense = .4 million, Debt = 4 million
Pre-tax cost of debt = .4/4 = 10%
After-tax cost of debt = 10% × (1 - .3) = 7%
**Step 3: WACC Calculation**
\[
WACC = w_e \cdot k_e + w_d \cdot k_d \cdot (1-T)
\]
\[
WACC = .6667 \times 17.04\% + .3333 \times 7\%
\]
\[
= 11.36\% + 2.33\% = 13.69\%
\]
**Final Answer for (b):**
**Cost of capital (WACC) = 13.69%**
---
## (c) **Estimate the Value of Faiba Technologies using the Firms Approach**
**Step 1: Calculate Free Cash Flow to Firm (FCFF)**
Earnings before interest & tax (EBIT) = 1.5 million
Less: Tax (30%) = 1.5 × .3 = .45 million
EBIT(1-T) = 1.05 million
Add: Depreciation = Capital Expenditure / 2 = 2 / 2 = 1 million
Less: Capital expenditure = 2 million
No change in working capital mentioned.
So:
\[
FCFF = EBIT(1-T) + Depreciation - Capital Expenditure
\]
\[
= 1.05 + 1 - 2 = .05\ \text{million}
\]
**Step 2: Project FCFF for next 5 years (growing at 20% per year)**
Let \(FCFF_ = .05\) million, growth rate (\(g_1\)) = 20%, discount rate (\(r\)) = 13.69%.
\[
FCFF_1 = .05 \times 1.2 = .06\ \text{million}
\]
\[
FCFF_2 = .06 \times 1.2 = .072\ \text{million}
\]
\[
FCFF_3 = .072 \times 1.2 = .0864\ \text{million}
\]
\[
FCFF_4 = .0864 \times 1.2 = .10368\ \text{million}
\]
\[
FCFF_5 = .10368 \times 1.2 = .124416\ \text{million}
\]
**Step 3: Terminal Value at Year 5 (growth rate after year 5 = 5%)**
Terminal Value = \(FCFF_6 / (r - g_2)\)
Where \(FCFF_6 = FCFF_5 \times 1.05 = .124416 \times 1.05 = .130637\) million
\(g_2 = 5\%\)
\[
TV_5 = \frac{.130637}{.1369 - .05} = \frac{.130637}{.0869} = 1.504\ \text{million}
\]
**Step 4: Present Value of FCFF and Terminal Value**
Discount each cash flow back to present using \(r = 13.69\%\)
\[
PV = \frac{FCFF_1}{(1+r)^1} + \frac{FCFF_2}{(1+r)^2} + \frac{FCFF_3}{(1+r)^3} + \frac{FCFF_4}{(1+r)^4} + \frac{FCFF_5 + TV_5}{(1+r)^5}
\]
Calculate discount factors:
Year 1: \(1/(1.1369)^1 = .8796\)
Year 2: \(1/(1.1369)^2 = .7736\)
Year 3: \(1/(1.1369)^3 = .6808\)
Year 4: \(1/(1.1369)^4 = .599\)
Year 5: \(1/(1.1369)^5 = .527\)
Now:
\[
PV_1 = .06 \times .8796 = .0528
\]
\[
PV_2 = .072 \times .7736 = .0557
\]
\[
PV_3 = .0864 \times .6808 = .0589
\]
\[
PV_4 = .10368 \times .599 = .0621
\]
\[
PV_5 = (.124416 + 1.504) \times .527 = 1.6284 \times .527 = .8576
\]
Add them up:
\[
\text{Total PV} = .0528 + .0557 + .0589 + .0621 + .8576 = 1.0871\ \text{million}
\]
**Final Answer for (c):**
**Estimated value of Faiba Technologies = sh. 1.09 million**
---
### **Summary of Answers**
(a) Cost of equity = **17.04%**
(b) Cost of capital (WACC) = **13.69%**
(c) Value of Faiba Technologies = **sh. 1.09 million**
VIPSolutions focuses on clear, step‑by‑step explanations so you can learn quickly. Whether you need an AI‑generated walkthrough or a short hint to get unstuck, each solution is organized for fast reading and easy review later.
Search similar questions, compare approaches, and bookmark the best answers for revision. Our goal is simple: quick, reliable study help that feels natural—not noisy.
 VIPSolutions
 QUESTIQH THREE
Faiba Technologies 1 a private firm owned by [ohn & Sons. I the most recent financial
period, the irm recorded revenues of sh. 10 milion on which it made eamings before,
*fnterest and taxes of LS million.
The firm had debt outstanding of sh. 4 million, on which pre-tax Interest expenses
amounted to sh. 044 million. The value of equity tn the firm's books Is indicated as 4
Tailion. The average beta of a publicly traded rms that are in the same business Is 1.5 and
the average debt-equity ratios 0.3 based upon market value of equity.
The market value of equity of this fim is, on average, two times the book value of equity.
All firms face a 30% tax rate.
capital expenditure amounted't5 sh. 2 milllon In the most recent year and
‘wice the depreciation charge in that year, Both items are expected to grow at the
rate as revenues for the next five years and to offset each other in steady state.
nutes of the firm are expected to grow 20 percenta year for the next five years, and
‘alter that. Net income and earnings before Interest and tax Is expected to
30 percent a year for the next five years, and 10 percentafier that .
bond rate {s 7% and the average return on the NSE-AS index is 13 percent.
‘Estimate the cost of equity for this private firm. £3
‘Estimate the cost of capital for this private firm. A
Estimate the value of atba technalogies sing the firms approach. L€ 14).