VIPSolutions logo ✨ VIPSolutions

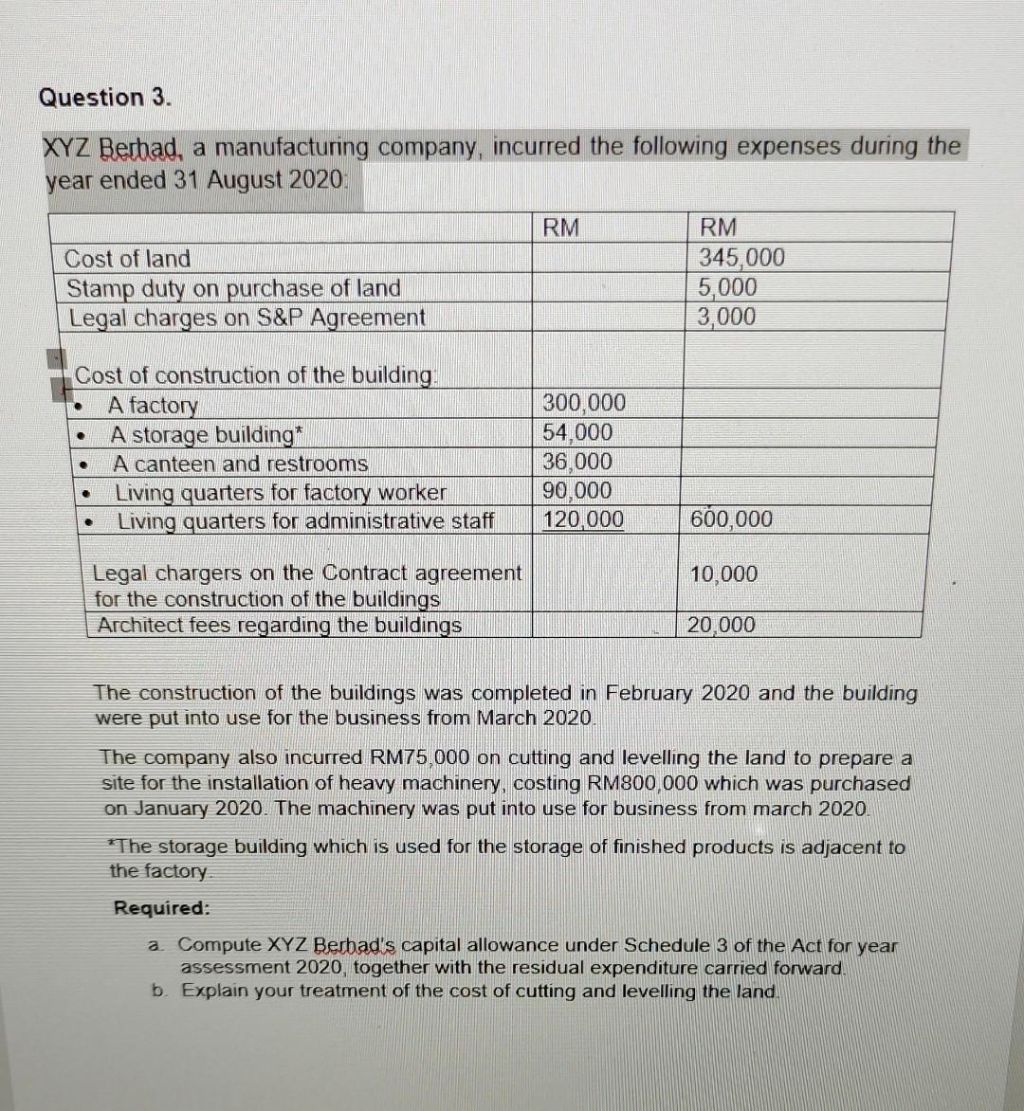
give full answer and give final summaryQuestion 3. XYZ Berhad, a manufacturing company, incurred the following expenses during the year ended 31 August 2020: Cost of land [EE ET 34s;000 Stamp duty on purchase of land WN E6000 Legal charges on S&P Agreement LEE E000=—) Cost of construction of the building = ww | A storage building” 54,000 = woo. rt — « Living quarters for factory worker 90,000 mE « Living quarters for administrative staff 120,000 600,000 Legal chargers on the Contract agreement 10,000 i for the construction of the buildings Architect fees regarding the buildings [EEE 20000 The construction of the buildings was completed in February 2020 and the building were put into use for the business from March 2020. The company also incurred RM75 000 on cutting and levelling the land to prepare a site for the installation of heavy machinery, costing RM800,000 which was purchased | on January 2020. The machinery was put into use for business from march 2020. ~ "The storage building which is used for the storage of finished products is adjacent to the factory. I I I \ Eagle ll i RARE a Compute XYZ Berhad's capital allowance under Schedule 3 of the Act for year RAN | assessment 2020, together with the residual expenditure Sled ward b. Explain your treatment of the cost of cutting and imi il nn I \ HE [HE mn a Il A. LE IH ll i . . i | | \ Nn LL | me—" od HI i IH Ii I | \ HA

Question:

give full answer and give final summaryUploaded ImageQuestion 3. XYZ Berhad, a manufacturing company, incurred the following expenses during the year ended 31 August 2020: Cost of land [EE ET 34s;000 Stamp duty on purchase of land WN E6000 Legal charges on S&P Agreement LEE E000=—) Cost of construction of the building = ww | A storage building” 54,000 = woo. rt — « Living quarters for factory worker 90,000 mE « Living quarters for administrative staff 120,000 600,000 Legal chargers on the Contract agreement 10,000 i for the construction of the buildings Architect fees regarding the buildings [EEE 20000 The construction of the buildings was completed in February 2020 and the building were put into use for the business from March 2020. The company also incurred RM75 000 on cutting and levelling the land to prepare a site for the installation of heavy machinery, costing RM800,000 which was purchased | on January 2020. The machinery was put into use for business from march 2020. ~ "The storage building which is used for the storage of finished products is adjacent to the factory. I I I \ Eagle ll i RARE a Compute XYZ Berhad's capital allowance under Schedule 3 of the Act for year RAN | assessment 2020, together with the residual expenditure Sled ward b. Explain your treatment of the cost of cutting and imi il nn I \ HE [HE mn a Il A. LE IH ll i . . i | | \ Nn LL | me—" od HI i IH Ii I | \ HA
This is AI generated Response.
Asked by: Dinil
Created at: 2026-01-06 01:26:41

Final Answer:

Rendered Raw Text
Did you like this answer?
## Question 3 Solution ### a. Compute XYZ Berhad’s Capital Allowance (CA) under Schedule 3 for Year of Assessment 202 #### **Step 1: Identify Qualifying Expenditure (QE)** **Only certain expenditures qualify for capital allowance** under Malaysian tax law (Schedule 3 of the Income Tax Act). Generally, QE includes costs incurred for: - Constructing/Acquiring industrial buildings (factory, storage, etc.) - Plant and machinery used for business - Excludes: Cost of land, stamp duty, legal fees on land purchase, living quarters for administrative staff, etc. #### **1. Industrial Building Allowance (IBA)** **Qualifying Expenditure:** | Description | Amount (RM) | Include as QE? | |----------------------------------------------|------------|--------------------| | Factory | 300,000 | Yes (Industrial) | | Storage building (for finished products) | 54,000 | Yes (Industrial) | | Canteen and restrooms | 36,000 | Yes (Industrial) | | Living quarters for factory worker | 90,000 | Yes (Industrial) | | Living quarters for admin staff | 120,000 | **No** | | Legal charges on contract (for construction) | 10,000 | Yes (Industrial) | | Architect fees (for building) | 20,000 | Yes (Industrial) | **Total Qualifying Expenditure (QE) for IBA:** ``` = 300,000 + 54,000 + 36,000 + 90,000 + 10,000 + 20,000 = RM 510,000 ``` *(Living quarters for admin staff is NOT qualifying.)* #### **2. Plant and Machinery Allowance** - **Machinery (purchased Jan 202):** RM800,000 - **Cutting and levelling land (preparing site for machinery installation):** RM75,000 (to be included as part of machinery QE) **Total QE for Plant and Machinery:** ``` = 800,000 + 75,000 = RM 875,000 ``` #### **Step 2: Compute Capital Allowance for YA 202** #### **Industrial Building Allowance (IBA):** - **Initial Allowance:** 10% - **Annual Allowance:** 3% **Since the building was put to use in March 202 (same YA), both allowances are claimable in YA202.** | Description | QE (RM) | Initial (10%) | Annual (3%) | Total CA 202 | Residual value c/f | |---------------------|---------|---------------|-------------|--------------|--------------------| | Industrial Building | 510,000 | 51,000 | 15,300 | 66,300 | 443,700 | --- #### **Plant & Machinery Allowance:** - **Initial Allowance:** 20% - **Annual Allowance:** 14% - *Machinery used from March 202.* | Description | QE (RM) | Initial (20%) | Annual (14%) | Total CA 202 | Residual value c/f | |----------------------|---------|---------------|--------------|---------------|--------------------| | Plant & Machinery | 875,000 | 175,000 | 122,500 | 297,500 | 577,500 | --- #### **Summary Table** | Asset Type | QE (RM) | CA 202 (RM) | Residual Expenditure c/f (RM) | |--------------------|---------|--------------|-------------------------------| | Industrial Building| 510,000 | 66,300 | 443,700 | | Plant & Machinery | 875,000 | 297,500 | 577,500 | --- ### b. **Treatment of Cutting and Levelling Land Cost** - The RM75,000 incurred for cutting and levelling land was for preparing the site for heavy machinery. - **Tax Treatment:** - This cost is **capitalized as part of the cost of plant and machinery** (NOT land or building). - It qualifies for capital allowance together with the machinery. - **Reference:** Para 55, Schedule 3, Income Tax Act 1967 – expenditure "for the purposes of preparing, cutting, tunnelling or levelling land in order to install plant and machinery" is included as qualifying expenditure for capital allowance. --- ## **Final Summary** - **Capital Allowance Claims for YA202:** - **Industrial Building:** QE = RM510,000; CA = RM66,300; Residual = RM443,700 - **Plant & Machinery:** QE = RM875,000; CA = RM297,500; Residual = RM577,500 - **Cutting and levelling land cost (RM75,000)** is treated as part of plant and machinery cost and qualifies for capital allowance. **Note:** Cost of land, stamp duty, legal fees on land purchase, and living quarters for admin staff do **not** qualify for capital allowance.

Question:

give 2 sentence summary in each questions

This is AI generated Response.
Asked by: Dinil
Created at: 2026-01-06 01:27:36

Final Answer:

Rendered Raw Text
Did you like this answer?
## Summary of Question 3 ### a. Capital Allowance Calculation XYZ Berhad's qualifying expenditure for capital allowance includes RM510,000 for industrial buildings and RM875,000 for plant and machinery. The total capital allowance for the year of assessment 2020 is RM66,300 for industrial buildings and RM297,500 for plant and machinery. ### b. Treatment of Cutting and Levelling Costs The RM75,000 spent on cutting and levelling land is capitalized as part of the cost of machinery and qualifies for capital allowance. This treatment aligns with Malaysian tax law, which allows such preparatory expenses to be included in the qualifying expenditure for capital allowance.

📢 Instructions:

  • Ask anything relatd to above question only.
  • For new Question goto :

Study Help, Fast Answers

VIPSolutions focuses on clear, step‑by‑step explanations so you can learn quickly. Whether you need an AI‑generated walkthrough or a short hint to get unstuck, each solution is organized for fast reading and easy review later.

Search similar questions, compare approaches, and bookmark the best answers for revision. Our goal is simple: quick, reliable study help that feels natural—not noisy.