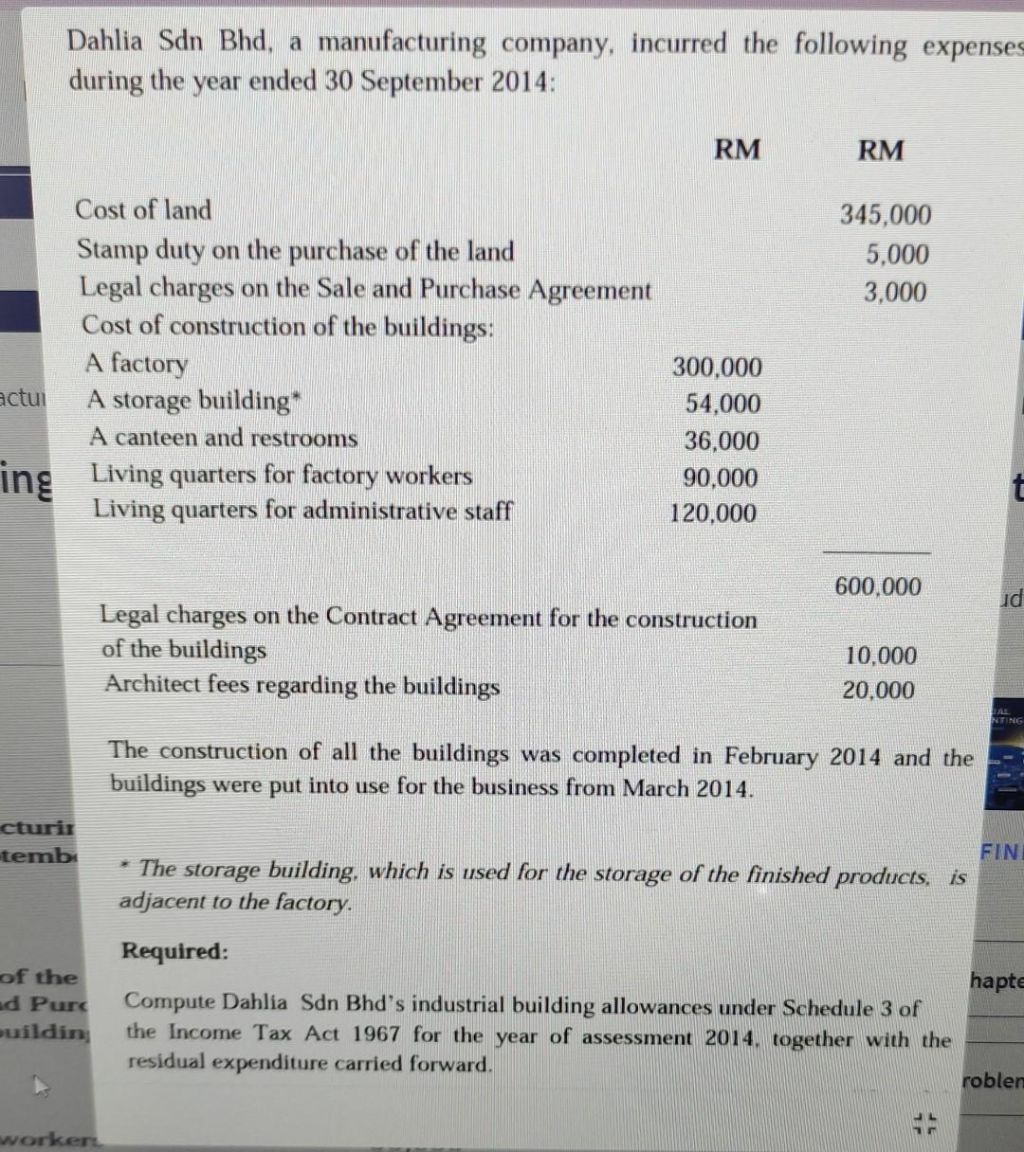
give full answer and give final summaryd Dahlia Sdn Bhd, a manufacturing company, incurred the following expense:
o during the year ended 30 September 2014:
il
I i
i RM RM
Bl Cost of land 345,000
~~ Stamp duty on the purchase of the land 5,000
a Legal charges on the Sale and Purchase Agreement 3,000
Bl Cost of construction of the buildings: |
~ Afactory 300,000
Ctl A storage building* 54,000 I
A canteen and restrooms 36,000 .
Ing Living quarters for factory workers 90,000
Living quarters for administrative staff 120,000 i
Legal charges on the Contract Agreement for the construction
= of the buildings 10,000
Architect fees regarding the buildings 20,000
The construction of all the buildings was completed in February 2014 and the
buildings were put into use for the business from March 2014.
* The storage building, which is used for the storage of the finished products, is
adjacent to the factory. I i
Rogan Li mn
Si tly bit LL A :
Compute Dahlia s I ing allowances unde ‘Sched le 3 of li I
the Income Tax Act 1967 papi of assessment 20 : Hig fll]
ll THIN TE ii il
Ea
" HH SE I HR a
RR | i) ie! i HA . | | a
Question:
give full answer and give final summaryd Dahlia Sdn Bhd, a manufacturing company, incurred the following expense:
o during the year ended 30 September 2014:
il
I i
i RM RM
Bl Cost of land 345,000
~~ Stamp duty on the purchase of the land 5,000
a Legal charges on the Sale and Purchase Agreement 3,000
Bl Cost of construction of the buildings: |
~ Afactory 300,000
Ctl A storage building* 54,000 I
A canteen and restrooms 36,000 .
Ing Living quarters for factory workers 90,000
Living quarters for administrative staff 120,000 i
Legal charges on the Contract Agreement for the construction
= of the buildings 10,000
Architect fees regarding the buildings 20,000
The construction of all the buildings was completed in February 2014 and the
buildings were put into use for the business from March 2014.
* The storage building, which is used for the storage of the finished products, is
adjacent to the factory. I i
Rogan Li mn
Si tly bit LL A :
Compute Dahlia s I ing allowances unde ‘Sched le 3 of li I
the Income Tax Act 1967 papi of assessment 20 : Hig fll]
ll THIN TE ii il
Ea
" HH SE I HR a
RR | i) ie! i HA . | | a
This is AI generated Response.
Asked by: Dinil
Created at: 2026-01-06 00:55:34
Final Answer:
RenderedRaw Text
Did you like this answer?
# Computation of Industrial Building Allowances (IBA)
**Dahlia Sdn Bhd – Year of Assessment 2014**
---
## Step 1: Identify Qualifying Expenditure
### **Eligible Costs for IBA under Schedule 3:**
- **Factory:** RM300,000
- **Storage building:** RM54,000
(Used for of finished products and adjacent to the factory)
- **Canteen and restrooms:** RM36,000
(If used by staff in the manufacturing process)
- **Legal charges on contract agreement (construction):** RM10,000
- **Architect fees:** RM20,000
#### **Not Eligible:**
- **Cost of land:** RM345,000 (Land is not a qualifying asset)
- **Stamp duty on land:** RM5,000
- **Legal charges on sale & purchase:** RM3,000
- **Living quarters for factory workers and admin staff:** RM90,000 + RM120,000 (Residential buildings not eligible unless they are integral to factory operations)
---
## Step 2: Calculate Total Qualifying Expenditure
| Description | Amount (RM) |
|----------------------|-------------|
| Factory | 300,000 |
| Storage building | 54,000 |
| Canteen/restrooms | 36,000 |
| Legal charges | 10,000 |
| Architect fees | 20,000 |
| **Total** | **420,000** |
---
## Step 3: Industrial Building Allowance Rates
For a **new building**:
- **Initial Allowance (IA):** 10%
- **Annual Allowance (AA):** 3%
### Calculation:
#### **Initial Allowance (IA):**
\[
IA = 10\% \times \text{RM420,000} = \text{RM42,000}
\]
#### **Annual Allowance (AA):**
\[
AA = 3\% \times \text{RM420,000} = \text{RM12,600}
\]
---
## Step 4: Apportionment for Year of Assessment
- Buildings were completed in February 2014 and used from March 2014 (used for >2/3 of the basis period, thus full year claim is allowed).
---
## Step 5: Residual Expenditure Carried Forward
\[
\text{Residual Expenditure} = \text{Qualifying Expenditure} - (\text{IA} + \text{AA})
\]
\[
= \text{RM420,000} - (\text{RM42,000} + \text{RM12,600}) = \text{RM365,400}
\]
---
# **Final Summary**
### **For the year of assessment 2014:**
- **Initial Allowance (10%):** RM42,000
- **Annual Allowance (3%):** RM12,600
- **Total Claim (2014):** RM54,600
- **Residual Expenditure Carried Forward:** RM365,400
**Only the factory, storage building, canteen/restrooms, legal charges for construction, and architect fees qualify for IBA. Land costs, stamp duty, legal charges on purchase, and living quarters do not qualify.**
Question:
give 2 sentence summary in each steps
This is AI generated Response.
Asked by: Dinil
Created at: 2026-01-06 00:56:27
Final Answer:
RenderedRaw Text
Did you like this answer?
# Summary of Steps for Industrial Building Allowances (IBA)
## Step 1: Identify Qualifying Expenditure
Dahlia Sdn Bhd's eligible costs for IBA include the factory, storage building, canteen/restrooms, legal charges, and architect fees, totaling RM420,000. Non-qualifying costs include land acquisition expenses and living quarters for staff.
## Step 2: Calculate Total Qualifying Expenditure
The total qualifying expenditure for IBA is calculated to be RM420,000. This amount will be used to determine the allowances available for the year of assessment.
## Step 3: Industrial Building Allowance Rates
The initial allowance is calculated at 10%, resulting in RM42,000, while the annual allowance is calculated at 3%, amounting to RM12,600. These allowances are based on the total qualifying expenditure.
## Step 4: Apportionment for Year of Assessment
Due to the buildings being used for more than two-thirds of the basis period, Dahlia Sdn Bhd can claim the full allowances for the year. This ensures that the company can utilize the tax benefits effectively.
## Step 5: Residual Expenditure Carried Forward
The residual expenditure after accounting for the initial and annual allowances is RM365,400. This amount can be carried forward for future tax claims, providing ongoing tax benefits to the company.
VIPSolutions focuses on clear, step‑by‑step explanations so you can learn quickly. Whether you need an AI‑generated walkthrough or a short hint to get unstuck, each solution is organized for fast reading and easy review later.
Search similar questions, compare approaches, and bookmark the best answers for revision. Our goal is simple: quick, reliable study help that feels natural—not noisy.
 VIPSolutions
 d Dahlia Sdn Bhd, a manufacturing company, incurred the following expense:
o during the year ended 30 September 2014:
il
I i
i RM RM
Bl Cost of land 345,000
~~ Stamp duty on the purchase of the land 5,000
a Legal charges on the Sale and Purchase Agreement 3,000
Bl Cost of construction of the buildings: |
~ Afactory 300,000
Ctl A storage building* 54,000 I
A canteen and restrooms 36,000 .
Ing Living quarters for factory workers 90,000
Living quarters for administrative staff 120,000 i
Legal charges on the Contract Agreement for the construction
= of the buildings 10,000
Architect fees regarding the buildings 20,000
The construction of all the buildings was completed in February 2014 and the
buildings were put into use for the business from March 2014.
* The storage building, which is used for the storage of the finished products, is
adjacent to the factory. I i
Rogan Li mn
Si tly bit LL A :
Compute Dahlia s I ing allowances unde ‘Sched le 3 of li I
the Income Tax Act 1967 papi of assessment 20 : Hig fll]
ll THIN TE ii il
Ea
" HH SE I HR a
RR | i) ie! i HA . | | a