 VIPSolutions
give answer in 2 step with explanation at the end of each step and final answer at the end:AEE EE I pra Que
Question:
give answer in 2 step with explanation at the end of each step and final answer at the end: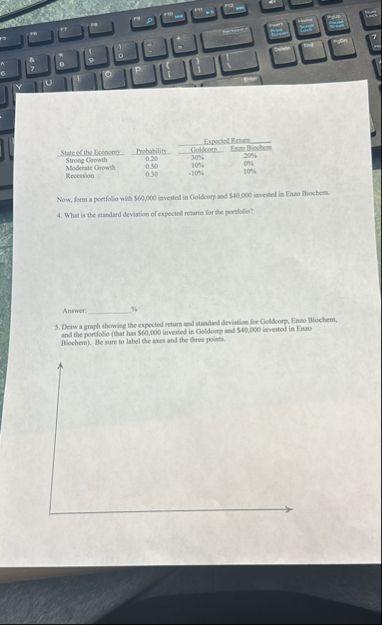 AEE
EE I pra Que
This is AI generated Response.
Asked by: Rahul
Created at: 2025-11-19 05:22:22
Asked by: Rahul
Created at: 2025-11-19 05:22:22
Final Answer:
Rendered
Raw Text
Did you like this answer?
Let's solve **Question 4: What is the standard deviation of expected returns for the portfolio?**
### **Step 1: Calculate Portfolio Expected Returns in Each State**
Let:
- $50,000 is invested in Goldcorp.
- $40,000 is invested in Enzo Biochem.
- Total portfolio = $90,000.
Weights:
- Goldcorp: \( w_G = \frac{50,000}{90,000} = .5556 \)
- Enzo Biochem: \( w_E = \frac{40,000}{90,000} = .4444 \)
For each state, portfolio return (\( R_p \)) is:
\[
R_p = w_G \cdot R_G + w_E \cdot R_E
\]
| State | Probability | Goldcorp (\(R_G\)) | Enzo Biochem (\(R_E\)) | Portfolio Return (\(R_p\)) |
|-----------------|-------------|--------------------|-------------------------|----------------------------|
| Strong Growth | .20 | 30% | 10% | \(.5556 \times 30\% + .4444 \times 10\% = 22.22\%\) |
| Moderate Growth | .50 | 10% | 7% | \(.5556 \times 10\% + .4444 \times 7\% = 8.33\%\) |
| Recession | .30 | -10% | 1% | \(.5556 \times -10\% + .4444 \times 1\% = -5.56\%\) |
**Explanation:**
We computed the weighted portfolio return for each economic state using the weights and expected returns.
---
### **Step 2: Calculate Portfolio Expected Return and Standard Deviation**
#### **A. Portfolio Expected Return (\(E[R_p]\)):**
\[
E[R_p] = (.20 \times 22.22\%) + (.50 \times 8.33\%) + (.30 \times -5.56\%)
\]
\[
= 4.444\% + 4.165\% - 1.668\% = 6.941\%
\]
#### **B. Portfolio Standard Deviation (\(\sigma_p\)):**
\[
\sigma_p = \sqrt{\sum P_i (R_{p,i} - E[R_p])^2}
\]
- For Strong Growth: \( (22.22\% - 6.941\%) = 15.279\% \)
- For Moderate Growth: \( (8.33\% - 6.941\%) = 1.389\% \)
- For Recession: \( (-5.56\% - 6.941\%) = -12.501\% \)
Now, square these differences, multiply by probability, and sum:
\[
\begin{align*}
&.20 \times (.15279^2) = .20 \times .02336 = .004672 \\
&.50 \times (.01389^2) = .50 \times .000193 = .0000965 \\
&.30 \times (-.12501^2) = .30 \times .015627 = .004688 \\
\end{align*}
\]
\[
\text{Sum} = .004672 + .0000965 + .004688 = .0094565
\]
\[
\sigma_p = \sqrt{.0094565} \approx .0972 = 9.72\%
\]
**Explanation:**
We calculated the expected return and then the standard deviation using the probability-weighted squared deviations from the mean.
---
## **Final Answer:**
**The standard deviation of expected returns for the portfolio is approximately \(9.72\%\).**
📢 Instructions:
- Ask anything relatd to above question only.
- For new Question goto :