 VIPSolutions
give answer in 2 step with explanation at the end of each step and final answer at the end:Consider the following details on the market portfolio and three other portfolios (X, Y, and Z). Portfolio Average annual portfolio return Portfolio standard deviation Portfolio beta Market 12% 16 % 1.00 X 13% 12% 0.85Y15% 25% 1.202 10% 8% 0.75 The yield on treasury bills is 6 percent. Required: a) Calculate the following ratios for managers’ X, Y, Z and the Market. (i) Treynor's value [5 marks] (ii) Sharpe's value [5 marks] (iii) Alpha value (Jensen's) [5 marks] b) Rank the managers’ performance. [5 marks]
Question:
give answer in 2 step with explanation at the end of each step and final answer at the end: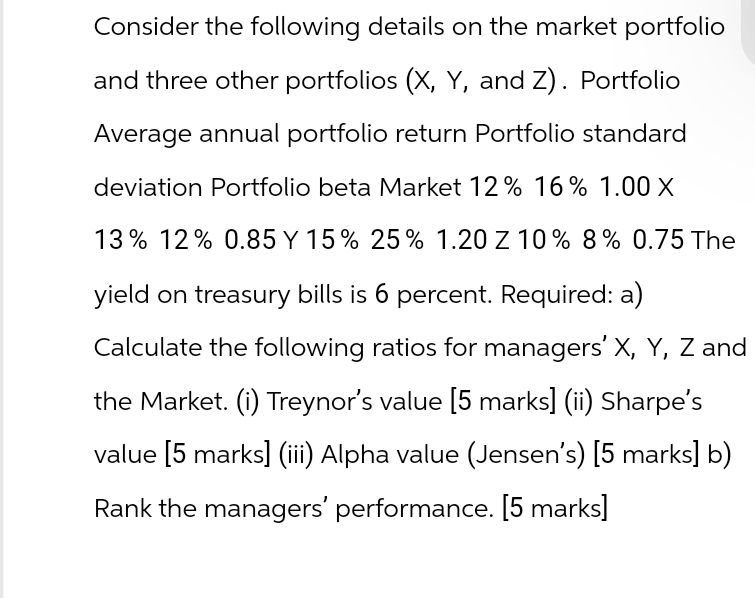 Consider the following details on the market portfolio
and three other portfolios (X, Y, and Z). Portfolio
Average annual portfolio return Portfolio standard
deviation Portfolio beta Market 12% 16 % 1.00 X
13% 12% 0.85Y15% 25% 1.202 10% 8% 0.75 The
yield on treasury bills is 6 percent. Required: a)
Calculate the following ratios for managers’ X, Y, Z and
the Market. (i) Treynor's value [5 marks] (ii) Sharpe's
value [5 marks] (iii) Alpha value (Jensen's) [5 marks] b)
Rank the managers’ performance. [5 marks]
This is AI generated Response.
Asked by: Rahul
Created at: 2025-11-13 03:10:22
Asked by: Rahul
Created at: 2025-11-13 03:10:22
Final Answer:
Rendered
Raw Text
Did you like this answer?
# Step 1: Calculate Treynor’s Ratio and Sharpe’s Ratio
### **Given Data**
- **Risk-Free Rate (\( R_f \))**: 6%
- **Market Portfolio:**
- Return (\( R_m \)): 12%
- Std Dev: 16%
- Beta: 1.00
- **Portfolio X:**
- Return: 13%
- Std Dev: 12%
- Beta: .85
- **Portfolio Y:**
- Return: 15%
- Std Dev: 25%
- Beta: 1.20
- **Portfolio Z:**
- Return: 10%
- Std Dev: 8%
- Beta: .75
---
### **Formulas**
- **Treynor’s Ratio:**
\[
\text{Treynor's Ratio} = \frac{R_p - R_f}{\beta_p}
\]
- **Sharpe’s Ratio:**
\[
\text{Sharpe's Ratio} = \frac{R_p - R_f}{\sigma_p}
\]
---
### **Calculations**
#### **Market**
- Treynor: \( \frac{12 - 6}{1.00} = 6.00 \)
- Sharpe: \( \frac{12 - 6}{16} = .375 \)
#### **X**
- Treynor: \( \frac{13 - 6}{.85} \approx 8.24 \)
- Sharpe: \( \frac{13 - 6}{12} = .583 \)
#### **Y**
- Treynor: \( \frac{15 - 6}{1.20} = 7.50 \)
- Sharpe: \( \frac{15 - 6}{25} = .36 \)
#### **Z**
- Treynor: \( \frac{10 - 6}{.75} = 5.33 \)
- Sharpe: \( \frac{10 - 6}{8} = .50 \)
---
#### **Step 1 Explanation**
We have calculated Treynor’s and Sharpe’s ratios for each portfolio using the provided returns, standard deviations, and betas. These ratios measure risk-adjusted performance, with Treynor using systematic risk (beta) and Sharpe using total risk (standard deviation).
---
# Step 2: Calculate Jensen’s Alpha and Rank Performance
### **Formula for Jensen’s Alpha**
\[
\alpha_p = R_p - [R_f + \beta_p (R_m - R_f)]
\]
---
### **Calculations**
#### **Market**
\[
\alpha = 12 - [6 + 1 \times (12 - 6)] = 12 - 12 =
\]
#### **X**
\[
\alpha = 13 - [6 + .85 \times (12-6)] = 13 - [6 + 5.1] = 13 - 11.1 = 1.9
\]
#### **Y**
\[
\alpha = 15 - [6 + 1.2 \times (12-6)] = 15 - [6 + 7.2] = 15 - 13.2 = 1.8
\]
#### **Z**
\[
\alpha = 10 - [6 + .75 \times (12-6)] = 10 - [6 + 4.5] = 10 - 10.5 = -.5
\]
---
#### **Ranking the Managers (Based on Ratios & Alpha):**
| Portfolio | Treynor | Sharpe | Alpha | Rank |
|-----------|---------|--------|-------|------|
| X | 8.24 | .583 | 1.9 | 1 |
| Y | 7.50 | .36 | 1.8 | 2 |
| Market | 6.00 | .375 | | 3 |
| Z | 5.33 | .50 | -.5 | 4 |
**Step 2 Explanation:**
Jensen’s Alpha measures the excess return above the CAPM-predicted return. Higher alpha indicates better performance. Based on all three metrics, Portfolio X consistently outperforms, followed by Y, Market, and Z.
---
## **Final Answer**
### **a) Calculated Ratios:**
| Portfolio | Treynor | Sharpe | Alpha |
|-----------|---------|--------|-------|
| Market | 6.00 | .375 | |
| X | 8.24 | .583 | 1.9 |
| Y | 7.50 | .36 | 1.8 |
| Z | 5.33 | .50 | -.5 |
### **b) Performance Ranking:**
**X > Y > Market > Z**
**Portfolio X is the best performer based on risk-adjusted return and alpha, followed by Y, Market, and Z.**
📢 Instructions:
- Ask anything relatd to above question only.
- For new Question goto :