VIPSolutions logo ✨ VIPSolutions

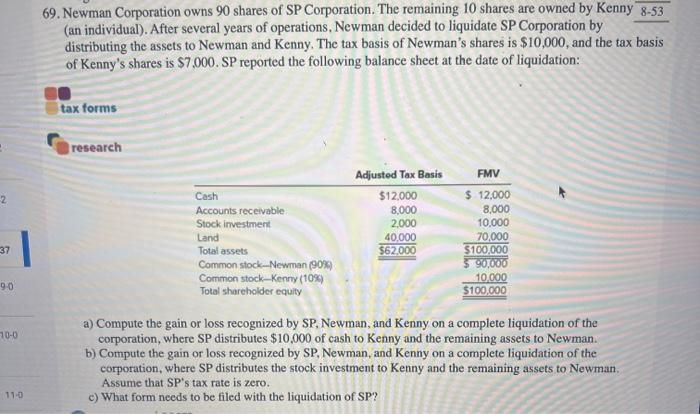
explain and give final summary). Newman Corporation owns 90 shares of SP Corporation. The remaining 10 shares are owned by Kenny" §.53 (an individual), After several years of operations. Newman decided to liquidate SP Corporationby === distributing the assets to Newman and Kenny. The tax basis of Newman's shares is $10,000, and the tax basis ~ of Kenny's shares is $7.00. SP reported the following balance sheet at the date of liquidation: = =. Ee ee : E — Adjusted Tax Basis MV — = 5 i Cash $12000 $ 12000 x — ] Roos tls som a0 — Sock mesiment 2000 10000 = m1 Land 0000 70000 - 37. < Tota assets F200 F000 = = 11. Comm ok Henin ||| SE ey : 3 he Common stock—Xeony (10%. 10000 = 4 he Toto! shareholder equity 0 Tom —_— a) Compute the gain or loss recognized by SP, Newman, and Kenny on a complete liquidation of the ~~ corporation, where SP distributes $10,000 of cash to Kenny and the remaining assets to Newman. b) Compute the gain or loss recognized by SP, Newman, and Kenny on a complete liquidation of the * corporation, where SP disibucs the sock investment (0 Kenny and te remaining assets to Nowra, Assume that SPs tx rat s zero. 31) - 2 ©) What orm needs tobe led with he luidaion of SP? EE Fs Po

Question:

explain and give final summaryUploaded Image). Newman Corporation owns 90 shares of SP Corporation. The remaining 10 shares are owned by Kenny" §.53 (an individual), After several years of operations. Newman decided to liquidate SP Corporationby === distributing the assets to Newman and Kenny. The tax basis of Newman's shares is $10,000, and the tax basis ~ of Kenny's shares is $7.00. SP reported the following balance sheet at the date of liquidation: = =. Ee ee : E — Adjusted Tax Basis MV — = 5 i Cash $12000 $ 12000 x — ] Roos tls som a0 — Sock mesiment 2000 10000 = m1 Land 0000 70000 - 37. < Tota assets F200 F000 = = 11. Comm ok Henin ||| SE ey : 3 he Common stock—Xeony (10%. 10000 = 4 he Toto! shareholder equity 0 Tom —_— a) Compute the gain or loss recognized by SP, Newman, and Kenny on a complete liquidation of the ~~ corporation, where SP distributes $10,000 of cash to Kenny and the remaining assets to Newman. b) Compute the gain or loss recognized by SP, Newman, and Kenny on a complete liquidation of the * corporation, where SP disibucs the sock investment (0 Kenny and te remaining assets to Nowra, Assume that SPs tx rat s zero. 31) - 2 ©) What orm needs tobe led with he luidaion of SP? EE Fs Po
This is AI generated Response.
Asked by: sreegeeth
Created at: 2025-07-27 10:22:56

Final Answer:

Rendered Raw Text
Did you like this answer?
Let's break down the problem step-by-step and provide a summary at the end. ## Given: - Newman Corporation owns **90 shares** (90%) of SP Corporation. - Kenny owns **10 shares** (10%) of SP Corporation. - The **tax basis** of Newman's shares: **$10,000** - The **tax basis** of Kenny's shares: **$7,000** - SP's reported balance sheet at liquidation: | Asset | Adjusted Tax Basis | FMV | |----------------------|-------------------|----------| | Cash | $12,000 | $12,000 | | Accounts receivable | $8,000 | $8,000 | | Stock investment | $2,000 | $10,000 | | Land | $40,000 | $70,000 | | **Total assets** | $62,000 | $100,000 | | Common stock—Newman | $55,800 | $90,000 | | Common stock—Kenny | $6,200 | $10,000 | | **Total equity** | $62,000 | $100,000 | --- ## (a) **Gain or loss recognized when SP distributes $10,000 cash to Kenny and remaining assets to Newman** ### 1. **SP Corporation's Gain or Loss** - **Liquidation is generally a taxable event** for C corporations. - SP will recognize gain/loss as if it sold the assets at FMV. - **Cash**: No gain/loss (FMV = basis) - **Accounts receivable**: No gain/loss (FMV = basis) - **Stock investment**: Gain = $10,000 (FMV) - $2,000 (basis) = **$8,000** - **Land**: Gain = $70,000 (FMV) - $40,000 (basis) = **$30,000** **Total gain recognized by SP:** $8,000 (stock) + $30,000 (land) = **$38,000** --- ### 2. **Distribution to Shareholders** - Kenny receives $10,000 cash (for his 10% interest) - Newman receives the remaining assets ($90,000 FMV, for his 90% interest) #### Kenny: - Amount received: $10,000 - Basis: $7,000 - **Gain:** $10,000 - $7,000 = **$3,000** #### Newman: - Amount received: $90,000 - Basis: $10,000 - **Gain:** $90,000 - $10,000 = **$80,000** --- ## (b) **SP distributes the stock investment to Kenny and remaining assets to Newman** - Kenny gets stock investment (FMV $10,000) for 10% interest. - Newman gets remaining assets (FMV $90,000) for 90% interest. #### Kenny: - Amount received: $10,000 (stock investment, FMV) - Basis: $7,000 - **Gain:** $10,000 - $7,000 = **$3,000** #### Newman: - Amount received: $90,000 (other assets, FMV) - Basis: $10,000 - **Gain:** $90,000 - $10,000 = **$80,000** --- ## (c) **Form to be filed** - **IRS Form 966** ("Corporate Dissolution or Liquidation") must be filed by the corporation within 30 days of the adoption of the resolution or plan to dissolve or liquidate. --- ## **Final Summary Table** | Party | Gain/Loss (a) | Gain/Loss (b) | Tax Form | |--------------|-------------------------|-------------------------|-------------| | **SP Corp** | $38,000 gain | $38,000 gain | Form 966 | | **Kenny** | $3,000 gain | $3,000 gain | | | **Newman** | $80,000 gain | $80,000 gain | | **Summary:** On liquidation, SP recognizes a total gain of $38,000. Kenny recognizes a gain of $3,000 and Newman recognizes a gain of $80,000, regardless of whether Kenny receives cash or the stock investment. SP must file IRS Form 966 for the liquidation.

📢 Instructions:

  • Ask anything relatd to above question only.
  • For new Question goto :

Study Help, Fast Answers

VIPSolutions focuses on clear, step‑by‑step explanations so you can learn quickly. Whether you need an AI‑generated walkthrough or a short hint to get unstuck, each solution is organized for fast reading and easy review later.

Search similar questions, compare approaches, and bookmark the best answers for revision. Our goal is simple: quick, reliable study help that feels natural—not noisy.