 VIPSolutions
Act like a helpful tutor and exlain step-by-step solution with explanation and final answer:According to CAPM, the expected return of a stock depends on: A. ts total risk B. Its beta C. Its dividend payout ratio D. Its accounting earnings
Question:
Act like a helpful tutor and exlain step-by-step solution with explanation and final answer: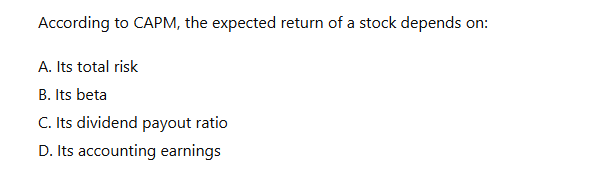 According to CAPM, the expected return of a stock depends on:
A. ts total risk
B. Its beta
C. Its dividend payout ratio
D. Its accounting earnings
This is AI generated Response.
Asked by: Francis
Created at: 2026-02-25 03:41:25
Asked by: Francis
Created at: 2026-02-25 03:41:25
Final Answer:
Rendered
Raw Text
Did you like this answer?
## Step-by-Step Solution
### Step 1: Understanding CAPM
**CAPM** stands for the **Capital Asset Pricing Model**. It is a model used to determine the expected return of an asset (like a stock) based on its risk compared to the overall market.
The CAPM formula is:
\[
E(R_i) = R_f + \beta_i [E(R_m) - R_f]
\]
Where:
- \(E(R_i)\) = expected return of the stock
- \(R_f\) = risk-free rate
- \(\beta_i\) = beta of the stock (a measure of its risk relative to the market)
- \(E(R_m)\) = expected return of the market
- \([E(R_m) - R_f]\) = market risk premium
### Step 2: Analyzing the Options
- **A. Its total risk**: CAPM does **not** use total risk. It only uses systematic (market) risk, not unsystematic (unique) risk.
- **B. Its beta**: **Beta** measures the stock's sensitivity to market movements (**systematic risk**), and it is the only risk factor in the CAPM formula.
- **C. Its dividend payout ratio**: Not used in the CAPM formula.
- **D. Its accounting earnings**: Not used in the CAPM formula.
### Step 3: Choosing the Best Answer
From the CAPM formula, **the expected return depends on the stock's beta**.
---
## **Final Answer**
**B. Its beta**
**Explanation:**
According to CAPM, the expected return of a stock depends on its beta, which measures its sensitivity to market movements (systematic risk), not its total risk, dividend payout, or accounting earnings.
📢 Instructions:
- Ask anything relatd to above question only.
- For new Question goto :