 VIPSolutions
Act like a helpful tutor and exlain me : Give step-by-step solution with explanation and final answer:A married couple is trying to finance their three - year - old son's college education. Money can be deposited at 6% compounded quarterly. What end-of - quarter deposit must be made from the son's 3rd birthday to his 18th birthday to provide $60,000 on each birthday from the 18th to the 21st? (Note that the first deposit comes three months after his 3rd birthday and the last deposit is made on the date of the first withdrawal.) Note - Solve only with the equations in the image, and nominal, quarterly, and effective interest types. F=pP+D)" P=Fa+i)" ~N a+ 1 Foal A=F———] a+p¥-1 N 1+ -1 poait -t +1 (1+) . ~N 1+ A= pt a+p¥-1
Question:
Act like a helpful tutor and exlain me :
Give step-by-step solution with explanation and final answer: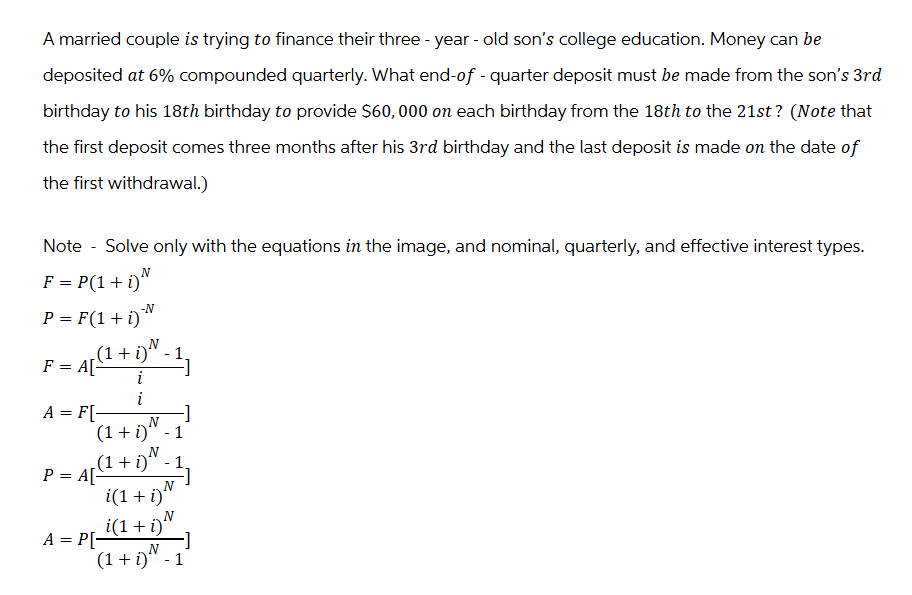 A married couple is trying to finance their three - year - old son's college education. Money can be
deposited at 6% compounded quarterly. What end-of - quarter deposit must be made from the son's 3rd
birthday to his 18th birthday to provide $60,000 on each birthday from the 18th to the 21st? (Note that
the first deposit comes three months after his 3rd birthday and the last deposit is made on the date of
the first withdrawal.)
Note - Solve only with the equations in the image, and nominal, quarterly, and effective interest types.
F=pP+D)"
P=Fa+i)"
~N
a+ 1
Foal
A=F———]
a+p¥-1
N
1+ -1
poait -t +1
(1+)
. ~N
1+
A= pt
a+p¥-1
This is AI generated Response.
Asked by: Smart Tv
Created at: 2025-09-18 08:42:41
Asked by: Smart Tv
Created at: 2025-09-18 08:42:41
Final Answer:
Rendered
Raw Text
Did you like this answer?
Let’s break this down step-by-step using the formulas **given in the image only**.
### **Step 1: Understanding the Problem**
- **Deposits:** Made quarterly (every 3 months) from the son's 3rd birthday until his 18th birthday.
- **Withdrawals:** $60,000 is withdrawn on each birthday from the **18th to the 21st** (i.e., 18th, 19th, 20th, and 21st birthdays). **4 withdrawals.**
- **Interest:** 6% compounded **quarterly**.
---
### **Step 2: Identify Variables**
- **Quarterly interest rate:**
\[
i = \frac{6\%}{4} = 0.06/4 = 0.015
\]
- **Number of deposits (quarters):**
- Age 3 to 18 = 15 years
- Each year has 4 quarters:
\( 15 \times 4 = 60 \) **deposits (N)**
- **Withdrawals:** $60,000 at the end of the 18th, 19th, 20th, and 21st years.
---
### **Step 3: Find the Present Value (P) of Withdrawals at the 18th Birthday**
The withdrawals are a series of 4 annual payments of $60,000 each, starting on the 18th birthday. Let's find their present value at the time of the 18th birthday (just before the first withdrawal).
Let’s use the present value of an ordinary annuity formula:
\[
P = A \left[ \frac{1 - (1 + i)^{-N}}{i} \right]
\]
But the formula given for the present value of an annuity is:
\[
P = A \left[ \frac{(1 + i)^N - 1}{i(1 + i)^N} \right]
\]
#### The withdrawal interval is **yearly**, but our rate is **quarterly**. So convert the number of quarters in 4 years:
- 4 years = 16 quarters
- Payment every 4 quarters, so let's use the effective annual rate:
- Effective annual rate:
\[
(1 + 0.015)^4 - 1 = 1.06136 - 1 = 0.06136 \approx 6.136\%
\]
But since the formula wants quarterly, let’s keep everything in quarters.
- \( A = \$60,000 \)
- \( N = 4 \) (withdrawals, but in quarters, so N = 16)
- Payments at the end of each year, i.e., every 4 quarters.
So, let's find the present value at the 18th birthday (time 0 for this step):
\[
PV = 60,000 \times (P/F, i, n) \text{ where } i = 0.015 \text{ per quarter, } n = 4 \text{ (years, but annual payments)}
\]
But the cash flows are:
- $60,000 at 0, 1, 2, 3 years from the 18th birthday (i.e., at 18, 19, 20, 21 years old).
Expressed in quarters, these are at 0, 4, 8, 12 quarters.
So,
\[
PV = 60,000 \times (1 + i)^{-0} + 60,000 \times (1 + i)^{-4} + 60,000 \times (1 + i)^{-8} + 60,000 \times (1 + i)^{-12}
\]
---
### **Step 4: Calculate the Present Value at the 18th Birthday**
Let’s calculate each term, with \( i = 0.015 \):
- \((1 + 0.015)^4 = (1.015)^4 = 1.06136\)
- \((1 + 0.015)^8 = (1.015)^8 = 1.1262\)
- \((1 + 0.015)^{12} = (1.015)^{12} = 1.1956\)
So present value at the 18th birthday:
\[
PV = 60,000 \left[1 + \frac{1}{1.06136} + \frac{1}{1.1262} + \frac{1}{1.1956}\right]
\]
Calculate each term:
- \(1/1.06136 = 0.9422\)
- \(1/1.1262 = 0.8881\)
- \(1/1.1956 = 0.8363\)
\[
PV = 60,000 \times (1 + 0.9422 + 0.8881 + 0.8363)
\]
\[
PV = 60,000 \times (3.6666)
\]
\[
PV = \$219,996
\]
---
### **Step 5: Find the Equivalent End-of-Quarter Deposit (A) from Age 3 to 18**
We want to accumulate $219,996 at the 18th birthday with quarterly deposits over 15 years (N = 60 deposits).
We use the **future value of an ordinary annuity** formula, rearranged to solve for A:
\[
F = A \left[ \frac{(1 + i)^N - 1}{i} \right]
\]
Solving for A:
\[
A = \frac{F \cdot i}{(1 + i)^N - 1}
\]
Here,
- \( F = 219,996 \)
- \( i = 0.015 \)
- \( N = 60 \)
Calculate \( (1 + 0.015)^{60} \):
\( \ln(1.015^{60}) = 60 \times \ln(1.015) = 60 \times 0.01489 = 0.8934 \)
\( e^{0.8934} = 2.443 \)
So,
\( (1.015)^{60} = 2.443 \)
Now plug into the formula:
\[
A = \frac{219,996 \times 0.015}{2.443 - 1}
\]
\[
A = \frac{3,299.94}{1.443}
\]
\[
A \approx \$2,287.24
\]
---
## **Final Answer**
### **The end-of-quarter deposit must be:**
\[
\boxed{\$2,287.24}
\]
**Explanation:**
You must deposit \$2,287.24 at the end of each quarter from your son's 3rd birthday until his 18th birthday (60 deposits) at 6% interest compounded quarterly to have enough for \$60,000 withdrawals on each birthday from his 18th to 21st.
📢 Instructions:
- Ask anything relatd to above question only.
- For new Question goto :