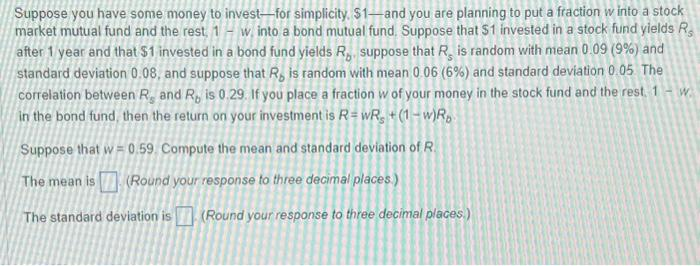
Suppose you have some money to invest—ior simplicity. $1—and you are planning to put a fraction w into a stack
market mutual fund and the rest. 1 = w, into a bond mutual fund, Suppose that $1 invested In a stock fund yields R;
after 1 year and that $1 invested in a bond fund yields R,. suppose that R, is random with ntean 0.09 (9%) and
Standard deviation 0.08, and suppose that R is random with mean 0 06 (6%) and standard deviation 0.05. The
| Correlation between Ry and R, is 0.29 If you place a fraction w of your money in the stock fund and the rest. 1 =
in the bond fund, then the return on your investment is R= WR + (1 w)R,
} HiT
1// Suppose that w = 059, Compute the mean and anda ovation oR
I £ tit
The means []. (Round your response fo threa dcr ii
| The standard deviation is [| (Round brides I places)
/ 1 TH
| Hi l | i LIL
Hi | i i HEL \
Question:
Suppose you have some money to invest—ior simplicity. $1—and you are planning to put a fraction w into a stack
market mutual fund and the rest. 1 = w, into a bond mutual fund, Suppose that $1 invested In a stock fund yields R;
after 1 year and that $1 invested in a bond fund yields R,. suppose that R, is random with ntean 0.09 (9%) and
Standard deviation 0.08, and suppose that R is random with mean 0 06 (6%) and standard deviation 0.05. The
| Correlation between Ry and R, is 0.29 If you place a fraction w of your money in the stock fund and the rest. 1 =
in the bond fund, then the return on your investment is R= WR + (1 w)R,
} HiT
1// Suppose that w = 059, Compute the mean and anda ovation oR
I £ tit
The means []. (Round your response fo threa dcr ii
| The standard deviation is [| (Round brides I places)
/ 1 TH
| Hi l | i LIL
Hi | i i HEL \
This is AI generated Response.
Asked by: Sunitha
Created at: 2025-07-24 15:35:39
Final Answer:
RenderedRaw Text
Did you like this answer?
Let's break down the problem and solve it step by step.
### **Given:**
- \( w = 0.59 \) (fraction invested in stock fund)
- \( 1-w = 0.41 \) (fraction invested in bond fund)
- \( R = wR_s + (1-w)R_b \)
- \( \mu_s = 0.09 \) (mean return of stock fund)
- \( \sigma_s = 0.08 \) (std dev of stock fund)
- \( \mu_b = 0.06 \) (mean return of bond fund)
- \( \sigma_b = 0.05 \) (std dev of bond fund)
- \( \rho = 0.29 \) (correlation between \( R_s \) and \( R_b \))
### **Mean of \( R \):**
\[
E[R] = wE[R_s] + (1-w)E[R_b] = w\mu_s + (1-w)\mu_b
\]
\[
E[R] = (0.59)(0.09) + (0.41)(0.06)
\]
\[
E[R] = 0.0531 + 0.0246 = 0.0777
\]
---
### **Variance of \( R \):**
\[
\text{Var}(R) = w^2\sigma_s^2 + (1-w)^2\sigma_b^2 + 2w(1-w)\rho\sigma_s\sigma_b
\]
Plug in the values:
\[
\text{Var}(R) = (0.59)^2(0.08^2) + (0.41)^2(0.05^2) + 2(0.59)(0.41)(0.29)(0.08)(0.05)
\]
Calculate each term:
- \( (0.59)^2 = 0.3481 \)
- \( (0.08)^2 = 0.0064 \)
- \( (0.41)^2 = 0.1681 \)
- \( (0.05)^2 = 0.0025 \)
- \( 2 \times 0.59 \times 0.41 = 0.4838 \)
- \( 0.29 \times 0.08 \times 0.05 = 0.00116 \)
- \( 0.4838 \times 0.00116 = 0.000561208 \)
Now sum the terms:
- \( 0.3481 \times 0.0064 = 0.00222784 \)
- \( 0.1681 \times 0.0025 = 0.00042025 \)
- \( 0.000561208 \)
Add them up:
\[
\text{Var}(R) = 0.00222784 + 0.00042025 + 0.000561208 = 0.003209298
\]
\[
\text{Std Dev}(R) = \sqrt{0.003209298} \approx 0.057
\]
---
### **Final Answers:**
- **Mean:** \( \boxed{0.078} \) (rounded to three decimal places)
- **Standard Deviation:** \( \boxed{0.057} \) (rounded to three decimal places)
Let me know if you need any further clarifications!
VIPSolutions focuses on clear, step‑by‑step explanations so you can learn quickly. Whether you need an AI‑generated walkthrough or a short hint to get unstuck, each solution is organized for fast reading and easy review later.
Search similar questions, compare approaches, and bookmark the best answers for revision. Our goal is simple: quick, reliable study help that feels natural—not noisy.
 VIPSolutions
 Suppose you have some money to invest—ior simplicity. $1—and you are planning to put a fraction w into a stack
market mutual fund and the rest. 1 = w, into a bond mutual fund, Suppose that $1 invested In a stock fund yields R;
after 1 year and that $1 invested in a bond fund yields R,. suppose that R, is random with ntean 0.09 (9%) and
Standard deviation 0.08, and suppose that R is random with mean 0 06 (6%) and standard deviation 0.05. The
| Correlation between Ry and R, is 0.29 If you place a fraction w of your money in the stock fund and the rest. 1 =
in the bond fund, then the return on your investment is R= WR + (1 w)R,
} HiT
1// Suppose that w = 059, Compute the mean and anda ovation oR
I £ tit
The means []. (Round your response fo threa dcr ii
| The standard deviation is [| (Round brides I places)
/ 1 TH
| Hi l | i LIL
Hi | i i HEL \